
Oil tops $100, Treasuries tag 5%, rate cuts are off the table. Warsh has three questions left tonight: hike 25, hold, or go more hawkish?
 2026/09/16 02:44
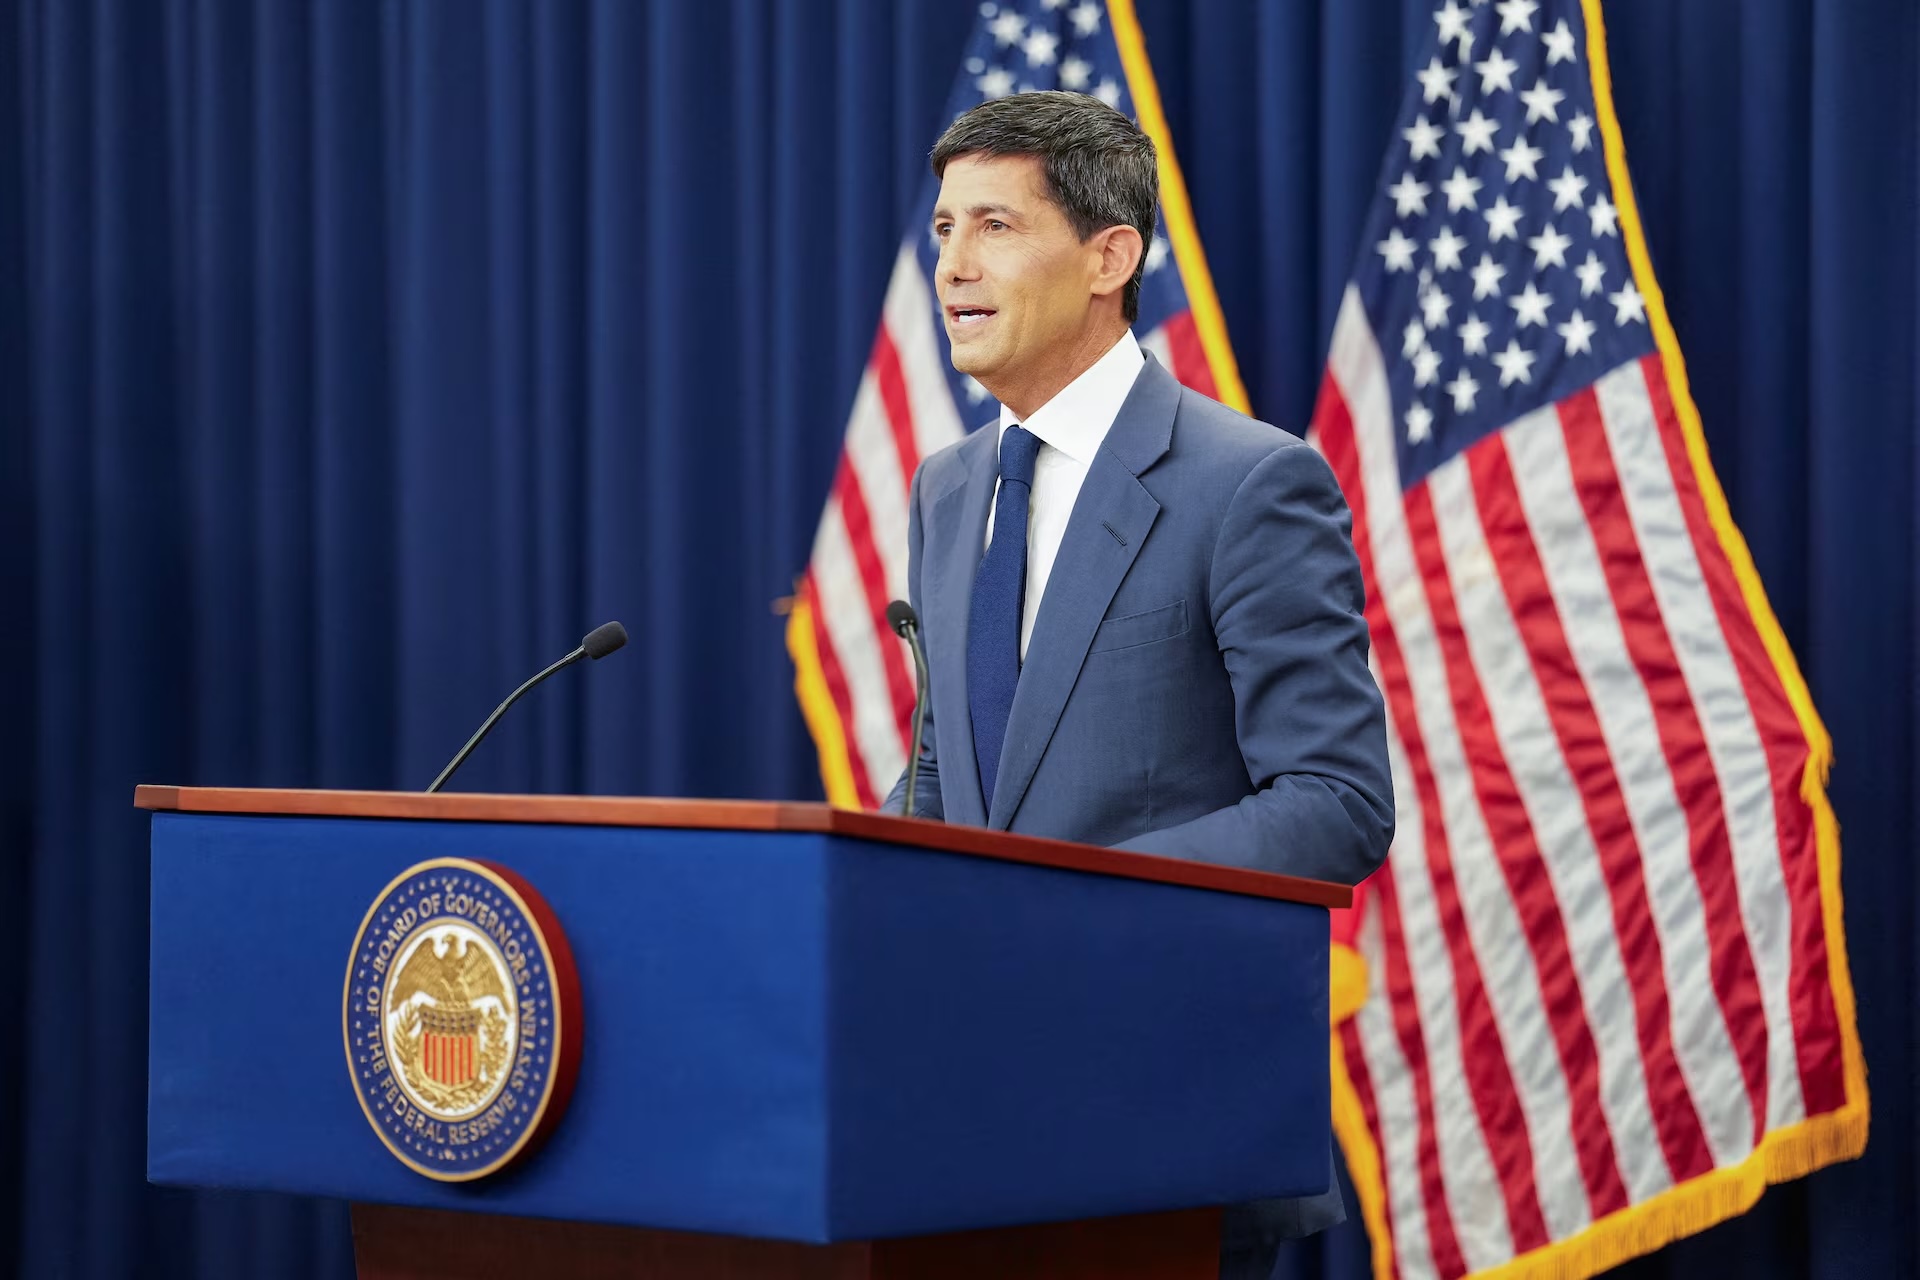
-
whether the vote is one-sided,
-
where the dots put the year-end rate,
-
how the statement talks about oil,
-
and whether Warsh talks tough at the podium.
-
A 25bp hike to 3.75%–4.00%, about 87%–90% odds. This is the base case.
-
A hold, about 10%–13% odds. That would be a dovish surprise.
-
A 50bp hike is under 2%. But a 25bp hike plus a sharply higher dot plot can still hit growth stocks. 25bp is mostly priced. What can actually reprice the tape is the dots and the press conference.
| Ticker | Sleeve | Why it fits |
| rXOM | Energy | Oil is above $100; the energy inflation premium is still there |
| rCVX | Energy | High-dividend cash machine; easier to trade than a single energy ETF |
| rJPM | Banks | Higher short rates feed large-bank net interest margin first |
| rGS | Investment banks | More volatility helps trading and deal flow |
| rRTX | Defense | Orders and geopolitics matter more than the multiple |
| Ticker | Sleeve | Why it fits |
| rNVDA | AI compute | Lower rates lift the multiple fastest |
| rTSLA | Growth | Long duration; most sensitive to rates moving down |
| rQQQ | Nasdaq ETF | One-ticket long on U.S. growth |
| rSOXL | 3x semiconductors | Chips already sold off Monday; bounce beta is high |
| rPLTR | AI software | High-multiple growth; first stop if money rotates back in |
| Ticker | Sleeve | Why it fits |
| rXOM | Energy | Cash cow; money leaving tech often lands here |
| rCVX | Energy | High yield, lower duration; holds up better in a hawkish tape |
| rSOXS | 3x inverse semis | Cleanest hedge if chip multiples get hit |
| rNEE | Utilities | Bond-like defense; relatively resilient in a rate scare |
| rPG | Staples | Steady earnings; less multiple damage than tech |
Stock Limited-time Offer:August new user gift: Buy U.S. stocks and get free NVIDIA stock.Trade Now for Better Deals
New to stock spot trading? These videos will get you up to speed:
"Understanding Bitget Spot Stock Trading"
"Spot Stock vs. Stock Perps vs. Traditional U.S. Stocks: Pros, Cons, Ownership & Leverage"
"How to Pick the Right Stock Tokens & ETFs on UEX? 2 Key Metrics to Help You Avoid Costly Mistakes"
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like

The 5% U.S. Treasury yield storm is coming! The refinancing time bomb countdown begins—who will be the first victim?
The 10-year US Treasury yield has surpassed 5%, reaching a new high since 2007. The longer high interest rates persist, the greater the refinancing pressure will be on real estate companies, commercial real estate, and highly indebted firms, with systemic risks likely to accelerate and emerge within the next 12 to 18 months.

Don't Fight the Profit Cycle! Will U.S. Stocks Break 8,000 Points This Year?
Jefferies predicts that, driven by the dual engines of the AI investment boom and stronger-than-expected corporate earnings, the S&P 500 index is expected to soar to 8,000 points by the end of 2026 and further reach 9,000 points in 2027. AI-driven profit expansion has spread from the "Magnificent Seven" to the entire market, with the S&P 500's EPS forecast to surge by 35% this year, far exceeding market consensus—marking the strongest earnings supercycle since 1995! The only real threat: if US Treasury yields continue to spike, the risk of valuation compression cannot be ignored.
Will “continual learning” AI extend the memory “shortage” until 2031?
Citi believes that as AI enters the era of "continuous learning" beyond simple training and inference stages, demand for HBM, server DDR5, and enterprise SSDs (eSSD) will experience explosive and simultaneous growth starting from 2027. While demand will surge rapidly, the supply side is constrained by HBM production capacity usage and slower technology migration, leading to expansion lagging far behind demand. This supply-demand imbalance is expected to continue until 2031.


