Oil prices fall back, easing inflationary pressure; gold rebounds above 4300, returning to the upper bound of the range
Huitong Network, September 18—— Gold rebounded to near $4,360 in Friday’s Asian session, recovering from a six-week low. The drop in oil prices to a one-week low and a weaker US dollar have improved gold’s short-term outlook, but the Federal Reserve’s persistent hawkish policy path and the probability of another rate hike in October rising to 53.1% mean gold prices are still constrained by both yields and the dollar.
Spot gold fluctuated and rose in Friday’s Asian session, with XAU/USD edging back towards $4,360, seeing some degree of technical correction after a rapid adjustment earlier. The rebound this round is mainly attributed to two factors: first, oil prices have fallen sharply, lowering energy costs and easing concerns about further inflation; second, the US dollar has weakened temporarily, reducing the exchange rate pressure faced by dollar-denominated gold. However, against the backdrop of the Federal Reserve’s latest hawkish policy signals, gold’s current rise is still more of a correction from lows, rather than a confirmation of a new one-way trend.
The changes in the energy market are once again influencing the pricing logic of precious metals. Recently, oil prices have fallen to a one-week low, with expectations rising that Middle Eastern supply disruptions may ease gradually. Saudi Arabia is seeking to partially restore oil transport along an important pipeline, further alleviating concerns about continuous supply tightness.
Recently, the linkage between energy prices and gold has strengthened. David Meger, head of metals trading at High Ridge Futures, stated that the marked drop in energy prices is easing gold-market burdens previously caused by inflationary pressures. For the current market, investors are focusing not only on safe-haven demand, but on whether oil price changes and inflation expectations can further influence US rates and the dollar. At the same time, a weaker dollar has improved gold’s short-term conditions. Gold is priced in US dollars; a stronger dollar typically increases the cost for investors using other currencies to buy gold, while a weaker dollar helps gold’s relative appeal. Previously, as gold prices kept slipping, simultaneous dollar strength and rising US treasury yields created dual pressure, so any slowdown in the dollar’s ascent makes it easier for gold to stage a rebound.
However, the biggest constraint on the gold market still comes from US monetary policy. Last Wednesday, the Federal Reserve raised its benchmark rate by 25 basis points to the 3.75%-4.00% range, with policy forecasts indicating at least one more hike this year. Rather than simply focusing on the hike itself, the market is more concerned whether the Fed will keep rates elevated and for how long this high-rate environment will persist. The CME FedWatch tool shows the current market expectation for another hike in October is about 53.1%, up from about 44% the previous trading day.
The recent performance of US treasury yields already proves interest rates are still an important suppressing force on gold. Market strategists noted that after the Fed’s decision, a strengthening dollar and higher treasury yields led to a significant fall in gold. The 2-year US treasury yield once approached 4.75%, and the 10-year yield edged close to 5%. Higher yields raise the opportunity cost of holding gold since gold itself generates no interest income. When risk-free or low-risk yields remain high, gold’s relative allocation appeal is affected. Nevertheless, the current price adjustment for gold does not mean the medium-term bullish logic is gone entirely. Some strategists believe a good part of the Fed’s hawkish rate path is already priced into assets. If, in the future, US economic data start to cool and the market revises down expected rates, Treasury yields and the dollar could both fall in sync, offering gold a chance to regain upward momentum. Thus, whether gold resumes a sustained uptrend will largely depend on whether US macro data can change the current rate pricing.
From a capital sentiment perspective, the fact that gold rebounded after falling to a six-week low shows that some funds are seeking low-level allocation opportunities again, but the market has not turned fully optimistic. The current price around $4,345 is still in a recovery phase following earlier declines, and investors remain highly sensitive to changes in the Fed’s policy path, the dollar, and yields. If the gold price fails to break key technical resistance, short-term capital may still choose to reduce holdings on rallies. The future trend of oil prices also deserves close attention. If Middle East oil supply gradually recovers and energy prices keep falling, market inflation expectations might cool further, helping ease upward rate pressure. Conversely, if supply recovery disappoints and oil prices rise again, energy costs could push inflation expectations higher, prompting the Fed to keep restrictive rates for longer, which would impose new pressure on gold.
Currently, three transmission chains need close attention. The first is whether oil prices will continue to fall; the second is whether US inflation and jobs data can alter October rate hike expectations; the third is whether the dollar and Treasury yields can weaken in sync.
From a daily chart perspective, spot gold has previously fallen for several sessions, hitting a six-week low, and has now rebounded towards $4,345. The price remains above the 100-day moving average, suggesting the medium-term bull structure remains intact, though the short-term trend has shifted from strong gains to post-correction consolidation. The current 100-day moving average, around $4,325, is a key support on the daily timeframe; as long as gold stays above this level, there is still room for further recovery. To the upside, the first hurdle is the middle band of the Bollinger Bands, near $4,435—a key resistance that this rebound needs to break. If gold can hold above $4,435, short-term bullish momentum could strengthen further, with a test of the upper band of the Bollinger Bands near $4,678 possible. However, there’s still a considerable gap between $4,678 and current prices, and without a clear weakening of the dollar and yields, it will be difficult for gold to break directly through this zone. The daily RSI is currently near 48.58, still in neutral territory—not overbought or oversold—suggesting neither bulls nor bears have a clear upper hand. The RSI’s neutrality matches the current price structure, meaning the market is currently searching for a direction rather than reversing trend. If $4,325 support fails, gold may retest the lower Bollinger Band near $4,190; whether this region holds will directly affect whether the medium-term uptrend remains intact.
On the 4-hour chart, gold has started a bounce from lows after a rapid drop, with short-term bearish momentum waning, but the rebound trend still needs to break above front resistance for confirmation. The current price is near $4,345, with $4,325 providing important short-term support. If gold holds above $4,325 and breaks through $4,435, the 4-hour structure could strengthen further; if it fails at $4,435 and drops back below $4,325, it shows the market is still in weak consolidation, and prices could test for support around $4,190 again. Overall, from a technical perspective, the current structure favors low-level consolidation and recovery, and a genuine trend reversal to strength needs to see a break of $4,435 with the dollar and yields falling simultaneously on a fundamental basis.
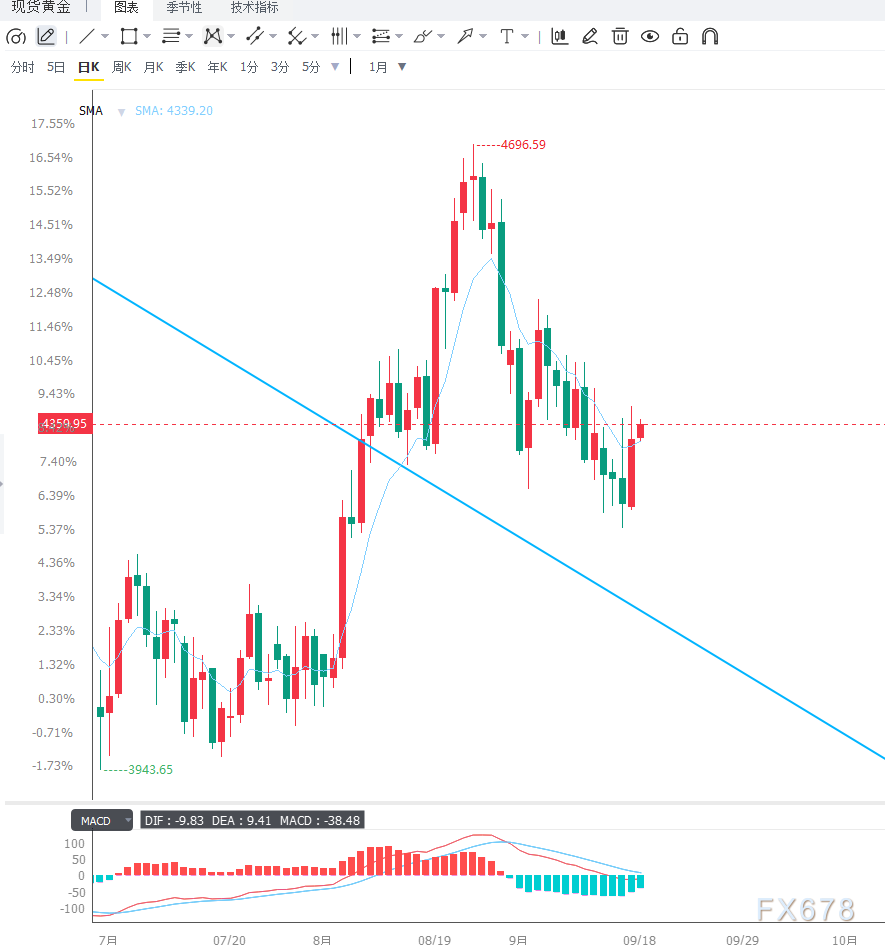
Gold is currently in a tug-of-war between a hawkish Fed and falling energy prices. Declining oil prices and a weaker dollar have given gold short-term rebound conditions, but with the Fed maintaining high rates and the probability of another rate hike in October rising to 53.1%, gold is still constrained by high opportunity costs.
From a technical standpoint, $4,325 is the current key support, while $4,435 is major resistance for the rebound to extend further. If the dollar and treasury yields keep falling, gold can continue its low-level recovery; if strong US data stokes further rate hike expectations, gold could again come under pressure. In the short term, market focus has shifted away from single safe-haven demand toward the linkages among oil prices, inflation, interest rates, and the dollar.





