Is the market less confident in US Treasury bonds than before?
👆Click the blue text to follow us
Term Premium
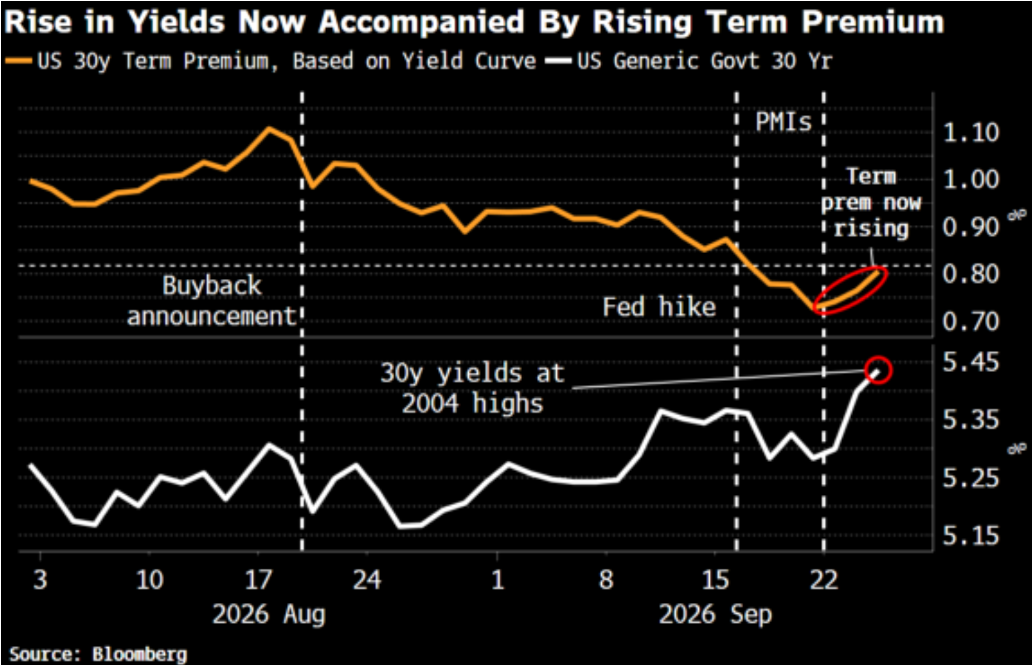
When it comes to the biggest current risk in the U.S. stock market, U.S. Treasury yields are definitely at the top of the list. Recently, the 10-year Treasury yield has become uncontrollable and reached as high as 5.16% intraday today. The 30-year yield has also climbed to 5.45%, the highest level since 2004. What is the fundamental reason behind the rising yields? And how will this ultimately affect the stock market? Today, a highly valuable internal Bloomberg analysis tackled these questions—let's take a look together.
Simon White, Bloomberg’s macro analyst, believes the reasons behind the continued rise in Treasury yields are beginning to shift. Previously, Treasury yields were rising because the market believed the Fed would continue to hike rates. According to White, this type of rise is a “good” one because it’s under the Fed’s control—where it goes and when it stops can mostly be predicted.
However, in yesterday’s rise of the 30-year yield, about half wasn’t due to rate hike expectations, but to the term premium. The term premium is the extra compensation investors demand for lending to the government over a longer period because the longer the time frame, the greater the uncertainty—which means more risk, so investors require more interest as compensation. This is the term premium. White points out that if the recent rise in Treasury yields is driven by the term premium, it shows investors are starting to feel uneasy about holding Treasuries long-term. This is something the Fed cannot directly control.
Take a look at this chart. The upper line is the term premium calculated by Bloomberg’s model, and the lower line is the 30-year Treasury yield. After the Treasury Department repurchased long-term Treasuries in August and after the Fed’s rate hike in September, term premiums were trending downward, easing some of the pressure on yields. But after the PMI data was released, the term premium reversed and started climbing, pushing the 30-year yield to new highs not seen since 2004.
So why do better PMI numbers make Treasuries riskier? White’s answer is: such strong PMI data means the government is spending lavishly, worsening fiscal issues. A large part of this round of economic growth is built on fiscal spending. Since 2020, the cumulative fiscal deficit in the U.S. has reached nearly $15 trillion, but with an average unemployment rate of only 4.8% and the economy not being bad, the government’s continuous big spending is very unreasonable. These massive deficits have boosted corporate profits and fueled huge capital expenditures and borrowing for AI infrastructure. Therefore, strong PMI data may paradoxically indicate irresponsible government spending, prompting more people to sell Treasuries and driving the term premium up.
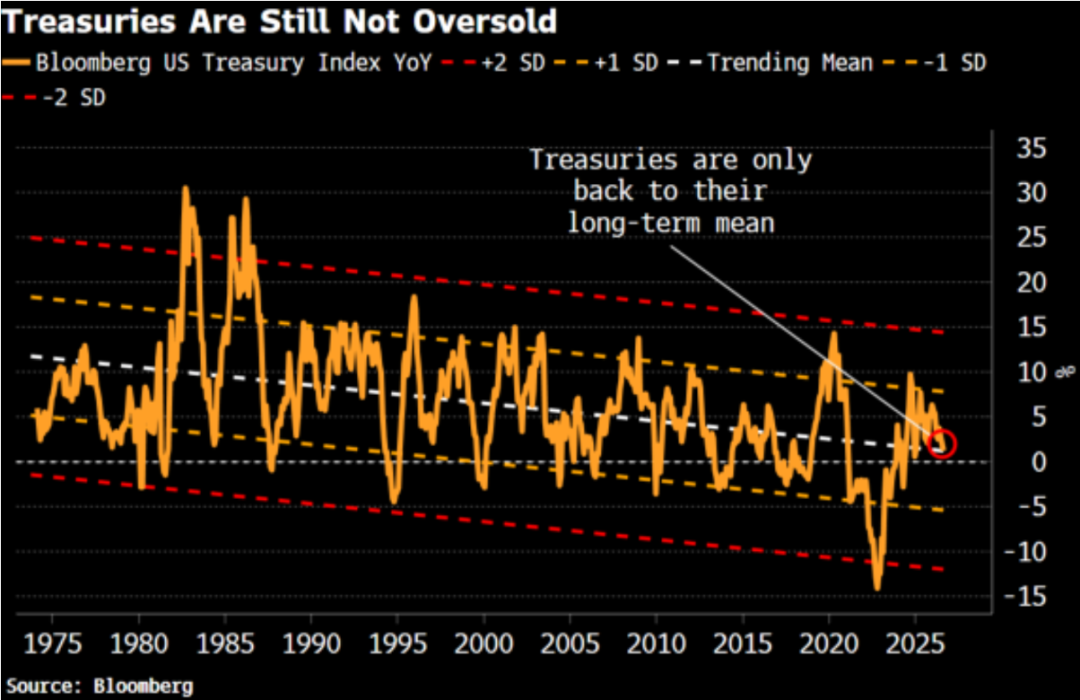
White also believes that although Treasuries have already declined, from a historical perspective, they are far from oversold. The Bloomberg-tracked Treasury index has only returned to its long-term trend average, and hasn’t even reached one standard deviation away. Thus, White believes if selling pressure continues, bond prices have more room to fall and yields could go even higher.
Additionally, White found that whenever the 10-year Treasury yield is above 5.25%, there’s hardly ever been a case where stocks fell and Treasuries rose. In other words, both the equity and bond markets tend to fall together. Normally, these two assets move in opposite directions, which helps reduce portfolio risk, but if both fall together, investors may sell even more Treasuries, pushing yields higher in a vicious cycle.
That’s the end of White’s analysis. Let’s now hear from Justin, the team’s analyst with the deepest understanding of U.S. Treasuries.
Justin believes that to push down long-term yields, two conditions must be met: room for the Fed to turn dovish, and a clear tightening of U.S. fiscal policy. However, neither condition has occurred and there’s little hope in the near term.
Looking at the Fed first: with the current strong economic demand and high oil prices, businesses have the ability to pass rising costs to consumers, making it even harder to bring inflation down. Under these circumstances, the Fed is unlikely to shift to easing just because long-term yields are climbing. As long as inflation, employment, and consumption don’t cool down obviously, the Fed’s main focus will be on controlling inflation.
As for fiscal issues, it goes without saying—by now, everyone knows just how severe the Treasury problem has become. According to the Congressional Budget Office, net interest payments by the federal government alone will exceed $1 trillion this year and double to $2.1 trillion by 2036. This will make borrowing increasingly expensive and the interest burden heavier, deepening the market’s concerns about America’s long-term fiscal stability.
Therefore, Justin believes that long-term yields will continue to face significant upward pressure. Even if the Fed stops hiking rates, long-term yields will remain elevated due to fiscal issues. For this reason, I think a long-term yield above 5% may become the new normal.
What does this mean for the stock market? First, there’ll likely be a shift from high-growth stocks to those with strong earnings certainty—something I mentioned yesterday. More importantly, there’s the possibility, highlighted by White, of both stocks and bonds falling as yields rise further. If this happens, it’s not just sector rotation anymore—given the current market leverage isn’t low. According to FINRA, investors borrowed about $1.45 trillion from brokers to buy stocks in August, up 37% from a year ago. This means that if both stocks and bonds fall, the value of collateral shrinks, and some investors could be forced to add margin or even sell assets, causing a chain reaction in the stock market. Therefore, if Treasury yields keep rising unstoppably, we need to prepare for near-term stock market corrections. We cannot always assume the stock market is immune—stay alert.
Contact us