Has US Treasury Bonds Bottomed Out? Goldman Sachs Trading Desk Head: Long-term Bonds are "Still Completely Unwanted"
The U.S. Treasury market is currently facing mounting pressures from multiple fronts. Yields on long-term Treasuries continue to rise, while buying interest remains unusually weak, further drawing attention to the growing divergence between bonds and equities.
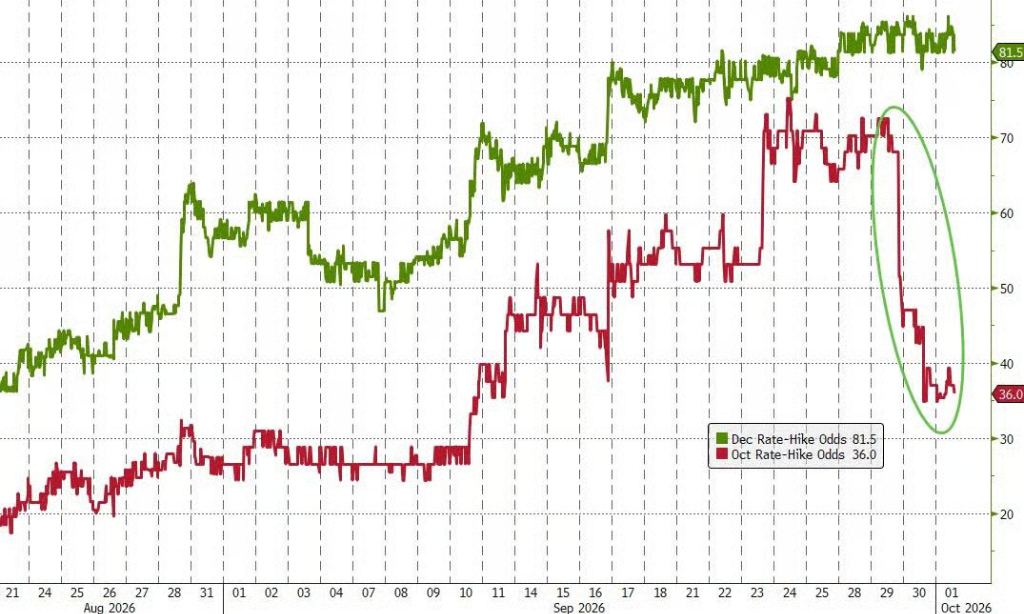
Rich Privorotsky, head of trading at Goldman Sachs, stated bluntly that “long-dated U.S. Treasuries are still completely neglected.” Although the latest PCE data came in lower than expected, slightly reducing the likelihood of a rate hike in October, it has had virtually no impact on long-term Treasury yields—the market has already priced in expectations for short-term rate hikes, with the true pressure now concentrated on the far end of the yield curve.
At the same time, expectations for volatility in long-term Treasuries have clearly decoupled from short-term rate market anxiety. Privorotsky summarized: “This situation urgently needs to be resolved.”
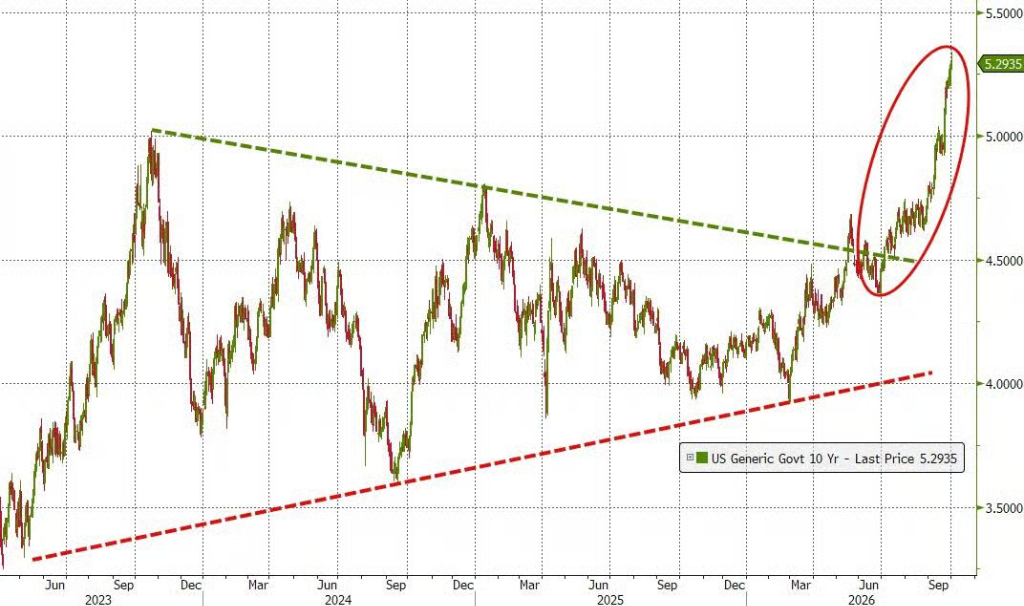
The rapid rise in yields is also triggering multiple warning signals based on historical patterns. Florian Roger from BNP Paribas CIB stated that a 5.5% yield on the 10-year Treasury is seen as the critical point at which it puts substantial pressure on equity markets: “We are very close to that level, at which point stock valuations will start to look overstretched.”
Simon White, macro strategist at Bloomberg, cautions that investors should not be deceived by seemingly low valuations—viewed against the historical performance of Treasuries themselves, yields may not have yet bottomed out.
Lack of Buying Interest in Long-dated Treasuries, No Rebound Yet in the Bond Market
The yield on the 10-year Treasury has risen to 5.34%, but even this level has yet to attract significant buyers. Although Treasuries look attractive from several valuation perspectives, market sentiment remains dominated by caution.
Simon White's analysis indicates that when comparing the 10-year Treasury yield with the average of U.S. nominal GDP growth and the 10-year Bund yield (excluding the pandemic and the Global Financial Crisis), the historical trajectories align closely—whereas the current Treasury yield stands well above this long-term average.
Meanwhile, the yield on the 10-year Treasury is more than 60 basis points higher than its fair value as estimated by a model incorporating global central bank rate hikes, yield curve dynamics, oil prices, and policy rates. Still, neither foreign nor domestic buyers have clearly stepped in.
Relative valuations between stocks and bonds are sending similar signals. The equity risk premium—measured as the difference between the earnings yield for the past 12 months and the 10-year Treasury yield—has dropped to a 20-year low, signaling equities are historically less attractive compared to bonds. Even when calculated on forward earnings, this measure is close to the historical low expected by 2025.
White points out that using the adjusted yield, which removes the term premium, provides a fairer comparison. By that metric, Treasuries still have some appeal, but the advantage has narrowed.
Mean Reversion Shows Oversold Levels Not Yet Reached
Although the above valuation indicators suggest Treasuries are relatively undervalued, White's alternative, more straightforward analytical framework—mean reversion of annual Treasury total returns—offers a more cautious signal.
This approach shows annual returns on Treasuries have historically oscillated around a mean value, typically overshooting below the mean in down cycles. Currently, annual Treasury returns are near the trend mean, but historical data suggests this point does not always mark the bottom. Based on over 50 years of historical data, in about three-quarters of instances where returns slid continuously for six months to around the mean, returns continued falling further over the next three months.
The trend in real yields also supports this assessment. The current uptick in nominal yields is largely driven by real yields, with breakeven inflation rates remaining relatively subdued. White’s leading indicator for the 10-year real yield, which incorporates excess liquidity, the pace of global central bank hikes, and the Federal Reserve policy rate, still points to more upside ahead in real yields. This indicator leads real yields by around three to four months.
Fiscal Pressures and Liquidity Risks Cannot Be Ignored
Potential buyers must also contend with the United States’ severe fiscal situation before stepping in.
Among major emerging and developed economies, the U.S. fiscal deficit as a share of GDP ranks among the highest globally, second only to Brazil, Poland, Hungary, and Colombia. Even after excluding interest expenses, the U.S. structural fiscal deficit still tops the global ranking—tied with the United Kingdom—making fiscal pressure impossible to ignore.
As yields continue to climb, market risks may become self-reinforcing. Higher yields can drive up volatility, affecting margin requirements and Treasury risk exposure limits; historically, higher volatility often coincides with deteriorating Treasury market liquidity.
White also notes that when the 10-year yield remains above 5.25% to 5.50% for an extended period, the historical correlation between Treasuries and equities typically turns sustainably positive, further undermining the role of Treasuries as a portfolio hedge.
Rising Expectations for Government Intervention, but No Strong Buy Signal
Under such pressure, expectations for policy intervention are rising. U.S. Treasury has reportedly hired Jefferies chief market strategist David Zervos as an advisor this week—a move that may not be coincidental. Zervos said in an interview that the Treasury is regaining control over debt maturity management and stressed “close attention must be paid to how this process develops.”
However, White cautions that while expectations for government intervention increase the risks associated with shorting, they are not sufficient to justify strong buying. If the market comes to rely on the government as a backstop, investors may be caught in a dilemma—neither comfortable shorting nor confident enough to go long—and should remain vigilant.
The core contradiction in the Treasury market now is this: valuations have improved, but multiple technical, fiscal, and liquidity constraints have yet to be resolved. Whether yields are truly near their bottom remains to be confirmed.