
US employment data supports restarting interest rate cuts in September, new SEC regulations cool down treasury companies, BTC weekly increase of 2.66% (09.01~09.07)

The new SEC regulations will slow down the pace and scale of acquisitions by treasury companies, which the market views as a significant bearish factor.
 The information, opinions, and judgments regarding markets, projects, and cryptocurrencies mentioned in this report are for reference only and do not constitute any investment advice.
Written by 0xBrooker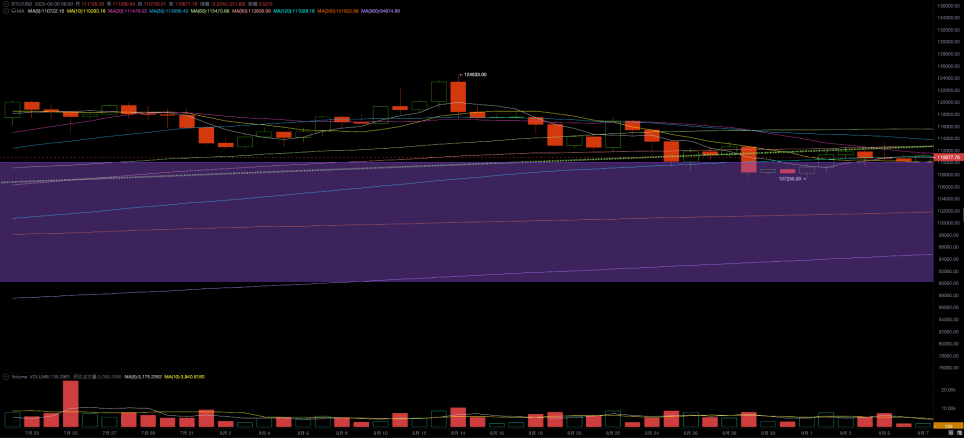
BTC Daily Chart Trend
BTC opened this week at $108,247.95 and closed at $113,478.00, with a low of $111,129.61 and a high of $113,390.00. The decline was 3.41%, the increase was 2.66%, and trading volume shrank compared to last week.
From a medium-term perspective, BTC is still in the midst of market turbulence caused by "rate cut revisions" and the "Federal Reserve independence game." In the short term, over the past week, BTC price has fluctuated further due to employment data and changes in industrial policy.
Employment data overall met the expectation of a "mild cooling," pushing the probability of a rate cut in September to around 90%. The expectation of three rate cuts within the year rebounded slightly, but remains low.
The SEC stated it will strengthen regulation over crypto treasury companies issuing additional shares to acquire cryptocurrencies. This has suppressed the financing activities of treasury companies, currently the largest source of buying power in the market, and is one of the reasons for the market's downturn.
EMC Labs maintains a cautiously optimistic attitude in the medium term. The rebalancing of market forces before and after the rate cut is bound to be turbulent, but the overall US economy is not at risk. The restart of the rate-cutting cycle supporting upward pricing of risk assets remains a certainty.
Policy, Macro Finance, and Economic Data
On September 4, the JOLTS job openings data was released first, with a published value of 8.4 million, lower than the expected 8.7 million and the previous value of 8.9 million, continuously declining to a three-year low, further confirming that labor demand is cooling.
On September 5, last week's initial jobless claims were released at 232,000, slightly higher than the market expectation of 230,000. Continuing jobless claims were 1.751 million, also slightly higher than the market expectation of 1.74 million. Both data points indicate the job market is slowing down.
On September 6, non-farm payroll data showed that 173,000 new jobs were added in August, lower than the market expectation of 180,000 and the previous value of 190,000. The unemployment rate simultaneously rose from 4.0% to 4.1%, reaching its highest point since 2021, indicating a clear cooling of the labor market.
The employment data showed a moderate "cooling," indicating that the economy and employment are slowing down, which has solidified the market's expectation for a September rate cut. FedWatch shows the probability of a September rate cut is close to 90%, with a small probability of a 75 basis point cut. This is a slight revision to last week's expectations.
Due to this revision, after two consecutive weeks of decline, US stocks rebounded this week. The Nasdaq rose 1.14%, the S&P 500 rose 0.33%, and all three major indices hit new intraday highs. Yields on both long- and short-term US Treasury bonds continued to fall, down 2.3% and 2.03% respectively.
There is no doubt about rate cuts, but the magnitude and frequency are still being priced in. The US Dollar Index fluctuated but fell 0.11% for the week to 97.737. Gold surged 3.52% to $3,639 per ounce.
Crypto Market
After a sharp downward revision last week, BTC rebounded by 2.66% this week, barely breaking through the "Trump bottom" ($90,000~$110,000 range), but is still suppressed by the "first bull market uptrend line" and remains below the 20-day moving average.
For the past two months, BTC has failed to launch the "fourth wave of increase" and has returned to the adjustment range. In addition to the impact of the rate-cutting cycle, this is also related to capital outflows and "cooling" policies.
According to eMerge Engine data, BTC Spot ETF channel funds have weakened for several consecutive weeks, and the scale of treasury company purchases has also dropped sharply.
On the regulatory front, the SEC released its latest opinion on crypto treasury companies (DATs) this week, bringing them under the national exchange/ATS regulatory agenda and requiring treasury companies to obtain shareholder approval before using diluted share financing to purchase crypto assets. This new regulation will undoubtedly slow down the speed and scale of treasury company acquisitions. The market sees this as a significant negative, with the stock prices of many treasury companies falling and exerting a negative impact on the trading prices of BTC, ETH, and others.
In addition to the cooling of industrial policy and capital inflows, long-term holders selling is also an important reason for BTC's price weakness. According to on-chain data, long-term holders reduced their BTC holdings by more than 40,000 this week, much higher than last week.
Currently, the coin price is close to the cost price of short-term holders, indicating that downside risk has already decreased.
Cycle Indicators
According to eMerge Engine, the EMC BTC Cycle Metrics indicator is at 0.375, in a mid-rise consolidation phase.
 EMC Labs was founded in April 2023 by crypto asset investors and data scientists. It focuses on blockchain industry research and secondary market crypto investment, with industry foresight, insight, and data mining as its core competencies. EMC Labs is committed to participating in the booming blockchain industry through research and investment, promoting blockchain and crypto assets for the benefit of humanity.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
SpaceX unlock wave meets index rebalancing! Goldman Sachs estimates: December rebalancing may bring $10.9 billion in passive buying
The proportion of SpaceX's freely tradable shares has increased from about 5% at the time of its IPO to one-third, and the expansion of index weightings is driving passive funds to increase their holdings. According to Goldman Sachs, the rebalancing of the Russell 1000 Growth Index on December 11 may trigger $10.9 billion in buy orders, with the main counterparts being insiders whose shares are unlocked. The S&P 500 inclusion window points to the second half of 2027, when the competition among passive funds will further intensify.
Citigroup Q3 Holdings: Nvidia (NVDA.US) Remains Top Heavy Position, Expanded Both Index and Tech Stock Options
According to the disclosure by the U.S. Securities and Exchange Commission (SEC), Citigroup (C.US) submitted its third quarter holdings report (13F) as of September 30, 2026, on November 4, 2026.

Carlyle still favors the healthcare sector in Q3, with Medline (MDLN.US) and StandardAero (SARO.US) accounting for over 98% of holdings
Carlyle (CG.US) has submitted its third-quarter holdings report (13F) for the period ending September 30, 2026.

Alphabet (GOOGL.US) reportedly plans to issue its first Hong Kong dollar and Singapore dollar bonds, potentially testing investor confidence amid growing concerns over AI financing.
Alphabet has recently held discussions about the potential issuance of its first Hong Kong dollar and Singapore dollar bonds. Amid global market volatility caused by sell-offs in artificial intelligence (AI) related sectors, this deal will test Asian investors’ appetite for subscription.

Crypto prices
More


