
Fed Faces a Choice: Boost Growth or Curb Mounting Debt?
- U.S. household debt hit $18.59 trillion in Q3 2025, driven by rising credit card, student loan, and home equity debt with delinquency rates at multi-year highs. - The Fed initiated rate cuts amid slowing job growth but faces a dilemma: easing economic strain risks inflating a consumer debt bubble while tightening worsens defaults. - Retailers, banks, and auto lenders face fallout as discretionary spending declines and loan defaults rise, while essential goods and debt collectors see increased demand. - P
As of the third quarter of 2025, American families are shouldering a record-breaking $18.59 trillion in debt, marking a $197 billion increase from the previous quarter, according to
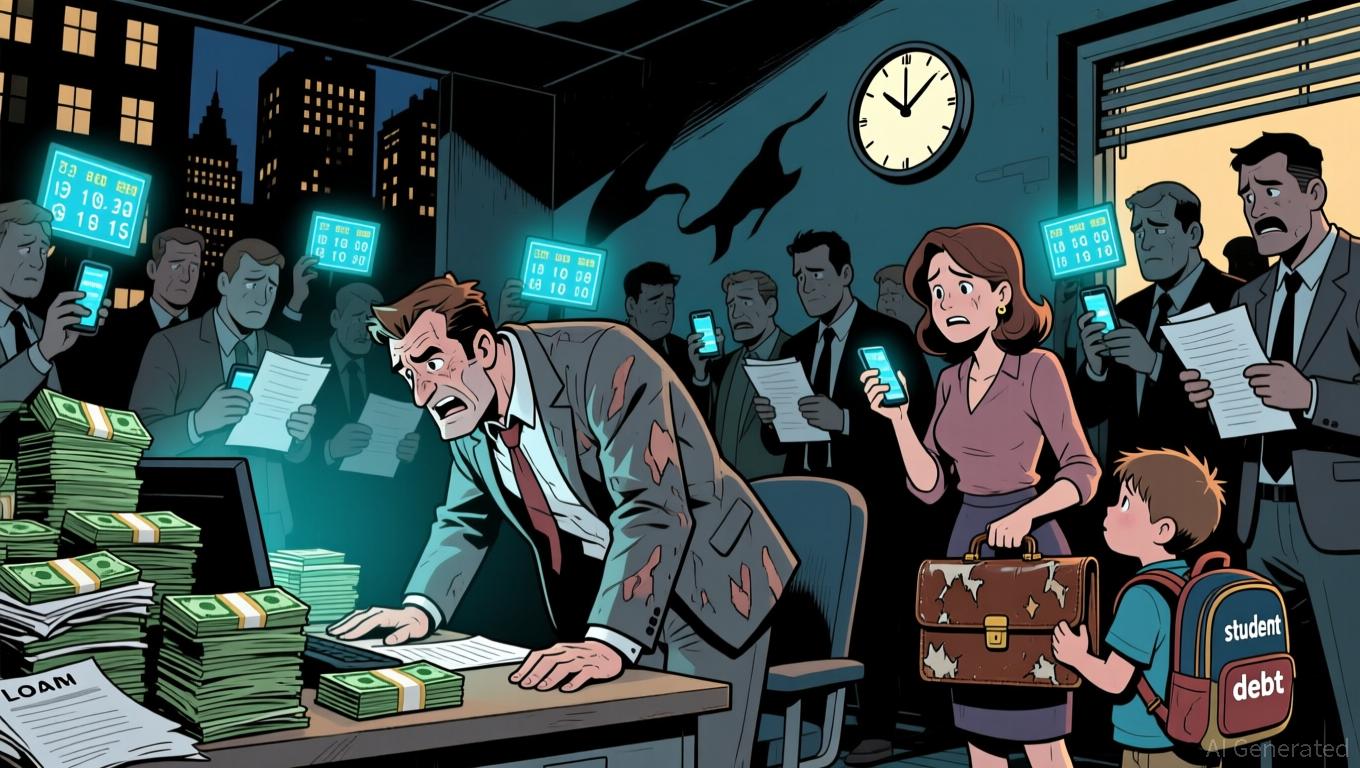
The Federal Reserve’s recent shift toward lowering rates, with a projected total reduction of 75 basis points in 2025, signals its growing concern about the economic strain from rising debt, the report continues. Still, experts caution that reducing rates may not significantly ease the pressure from existing high-interest obligations. “The Fed is in a precarious position,” one economist commented, explaining that while rate cuts could encourage more borrowing for homes and businesses, they also risk further inflating the consumer debt bubble, according to the analysis.
This surge in debt is prompting companies—especially in retail, finance, and automotive industries—to rethink their strategies. Retailers selling non-essential goods, such as luxury brands and travel services, are seeing demand drop as families focus on necessities, the FinancialContent article notes. Meanwhile, traditional banks and credit card companies are preparing for a rise in loan defaults.
On the other hand, retailers specializing in essentials like Walmart and Costco continue to see steady demand, and companies in healthcare and utilities remain largely unaffected by shifts in consumer spending. Debt collection firms and lenders with varied sources of income are also profiting from the uptick in delinquencies.
The Federal Reserve’s predicament reflects wider global patterns. While mortgage loans remain relatively healthy due to strong home equity, the increase in non-mortgage delinquencies points to an uneven recovery. The central bank’s Financial Stability Report identifies high business debt and rising consumer loan defaults as major systemic threats, leading to calls for more targeted policy responses, the report says.
Looking forward, forecasts suggest the U.S. economy will expand by just 1.7% in 2025 and 1.4% in 2026, with inflation rates averaging 2.9% and 3.2% respectively, according to the analysis. The Fed’s anticipated rate cuts, expected to lower the federal funds rate to between 3.50% and 3.75% by late 2026, are intended to support a weakening job market while keeping inflation in check. However, ongoing tariffs and policy uncertainties could complicate these efforts.
The Federal Reserve’s upcoming decisions will depend on critical economic data. Reports on manufacturing and retail sales, due in early November, may influence future rate changes, according to the
With the debt crisis worsening, investors are watching delinquency rates and Fed policy closely. The next few months will be a test of the central bank’s ability to steer the economy through these challenges without triggering a wider financial downturn, the FinancialContent report concludes.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
 VIPAI Asset Sell-Off and Selective Rotation in Crypto
1. Technology stocks fell sharply as investor interest shifted toward energy and selected defensive assets. From October 10 to 16, the Nasdaq 100 declined 5.49% and the S&P 500 fell 1.95%, while the Dow gained 0.67% and WTI crude rose 10.41%. BTC, ETH, and SOL declined 1.27%, 2.65%, and 4.44%, respectively. This week's technology earnings will be an important test of whether revenue growth, margins, and cash flow can justify current valuations. Better-than-expected results could help stabilize markets in the near term. 2. Crypto continues to see pockets of strong activity, but a broad-based altcoin season has yet to materialize. CoinMarketCap's (CMC) Altcoin Season Index stood at 54 as of the October 18 UTC daily observation, below the altcoin-season threshold of 75, while BTC dominance rose to 60.08%. Our proxy leverage ratio fluctuated between 4.00 and 4.07 during the week, showing no sustained increase and suggesting limited appetite for additional leverage. Meanwhile, as major exchanges expand access to traditional financial assets, the recent sell-off in AI-related equities could attract short-term speculative capital away from crypto. Such capital rotation could make it more difficult for a new altcoin season to take hold. 3. Papertrade's loss-to-mine model has generated significant interest across the crypto community. The protocol combines high-leverage derivatives trading with zero slippage and a mechanism that rewards trading losses with PAPER tokens. Across the eight complete UTC days from October 10 to 17, cumulative reported revenue reached approximately $56.08 million, including $51.90 million distributed to token holders. With growing participation from key opinion leaders (KOLs), Papertrade has reportedly ranked among the top three platforms by profitability in the broader market recently. Assets to watch: BTC, ETH, SOL, ARB, OP, SKHYNIX, SKHY, META, TSLA, LRCX, and SPCX. Key research priorities this week: Cash flow performance in technology earnings; the relative discount and holding costs of the two SK Hynix contracts; and U.S. initial jobless claims and PMI data. Weekly market data cover the period through October 16, while research information was verified through October 18. Observation periods are specified separately for each chart.
Why Bernstein Thinks the AI Stock Sell-Off Could Help Small Caps

Morgan Stanley Builds Crypto Lab to Test Stablecoins, Tokenization and DeFi at Scale
Top 4 Earnings Reports This Week: What Tesla, Meta, SpaceX, Netflix Must Show
Crypto prices
More


