
Why are institutions continuing to raise their holdings of TSMC at this level?

Hello everyone, this is You Dou.
After TSMC released its 4Q25 earnings report, the market responded quickly.
But the real question worth asking is:
Why did institutions choose to continue raising TSMC at this point?
This question is not answered based on intuition.
In this article, I mainly combined the latest research reports released by J.P. Morgan and Goldman Sachs after the earnings report, and from the perspective of institutional models, analyzed why they chose to continue the upward revision at this timing.
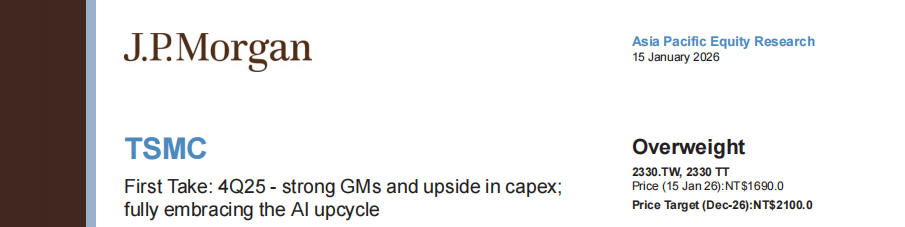
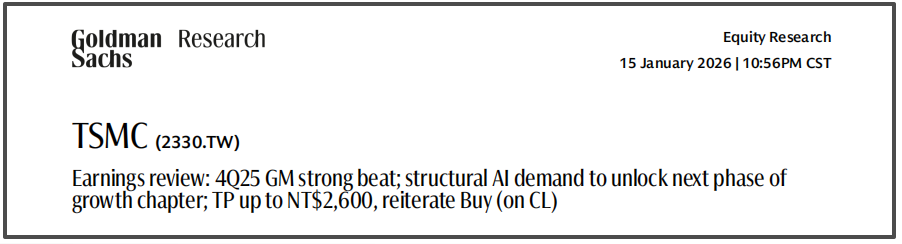
Let me give the conclusion first.
This round of upward revision is not because the earnings report looks “good,” but because the original assumptions can no longer stand.
Whether it’s J.P. Morgan or Goldman Sachs, there’s only one thing in common about this move:
It’s not a minor adjustment, but a change in long-term assumptions.
This change is mainly reflected in three aspects.
First Level Reason: AI is No Longer a Marginal Variable
In the past few years, institutional judgment on TSMC’s AI-related revenue was mostly:
Growth is rapid, but it’s still just a subcategory in HPC, with limited impact on long-term models.
After this earnings report, this positioning was completely overturned.
Institutions now generally consider AI accelerator-related revenue as:
the core variable determining advanced process utilization rates
the core variable determining the pace of capital expenditure
and even a variable that determines the overall growth slope of the company
When AI shifts from being “optional” to the “main variable,”
the original growth model naturally needs to be elevated as a whole.
This is not bullish sentiment, but a structural change.
Second Level Reason: 60% Gross Margin Is Becoming the “Norm”
If the revenue side changed the growth slope,
then what changed on the profit side is the valuation anchor itself.
What’s truly important in this earnings report is not that a single quarter’s gross margin exceeded expectations, but that three things happened simultaneously:
4Q25 gross margin stabilized above 60%
1Q26 guidance further raised
Long-term gross margin guidance was clearly raised
The implication behind this is:
Institutions are starting to accept a new premise—
In the coming years, TSMC’s gross margin center may not return to just above 50%.
Once the gross margin center is confirmed to be elevated:
the change in EPS is no longer linear,
but rather the entire profitability range is raised.
This is also why many upward revisions are not achieved by simply increasing the valuation multiple, but by re-pricing EPS.
Third Level Reason: The “Nature” of Capex Has Changed
There has always been controversy in the market over TSMC’s Capex.
But the key to the institutional change in judgment this time is not about how big Capex is, but about why Capex needs to be so large.
This time, institutions characterize Capex as:
not a countercyclical gamble
not a defensive investment
but rather an early layout driven by the long-term certainty of AI demand
In other words:
Capex is no longer regarded as a risk variable, but as the result of growth visibility.
When Capex is understood this way, its meaning for valuation is completely different.
Why Continue Raising “Now” Instead of Earlier or Later?
This is a key question that many people tend to overlook.
Institutions didn’t just realize today that AI is important,
nor did they just now see the tightness in advanced process capacity.
The real trigger is that three things were validated at the same time:
1️⃣ AI demand is no longer just order noise, but a sustainable curve
2️⃣ Gross margin has not been significantly pressured by capacity expansion and overseas deployment
3️⃣ Management has become more decisive regarding medium- and long-term Capex
When all three conditions are met simultaneously,
the original “cautious assumptions” must be revised.
That’s also why the upward revision happened at this point, rather than before the earnings report.
My Understanding
If you only look at the stock price, this upward revision may seem a bit “going with the flow”;
but from the institutional model’s perspective, this is a correction that had to be made.
TSMC is shifting from:
“A highly cyclical manufacturing company”
to:
“The core asset with structural profitability in the AI infrastructure era.”
In this context,
institutions continuing to raise is not aggressive, but lagging.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
With future spending commitments amounting to $883 billion putting pressure on the company, Amazon opens another financing channel of up to $8 billion to support AI expansion
Amazon has secured a loan facility of up to $80 billion for the procurement of technology infrastructure assets, which can be utilized between the first quarter of next year and the third quarter of the following year. As of the end of September this year, Amazon's total spending commitments reached $883 billion, an increase of 36% compared to three months ago and more than double that of a year earlier.
Forecasting the upcoming week: US midterm elections, Payrolls and BoE in the spotlight
Intel: PC Market Falters First, Foundry Plans Still "To Be Discussed Later"
Server orders are still queued, and AI demand hasn't collapsed. What has changed is pricing: PCs are constrained by memory costs, gross margin guidance is being revised downward, and external OEMs still can't be incorporated into the model. Next year, free cash flow is also likely to turn negative. The market is no longer willing to pay for an unfulfilled OEM timeline or the pace of PC recovery.
Crypto prices
More


