
The Surge in Micron Technology Stock Looks Poised to Continue

Being a leading provider of semiconductor memory solutions, Micron Technology MU is the most searched for stock on Zacks.com outside of Nvidia NVDA.
This comes as the storied memory chip shortage has made Micron a central beneficiary of the AI hardware boom.
The rapid expansion of AI hardware — data centers, GPUs, and accelerators — is consuming most of the memory chip supply and bandwidth, driving a sharp increase in demand for Micron’s offerings.
With the demand shock being structural and not a temporary spike, Micron’s stock more than tripled last year and is already up more than 40% in 2026.
While this is an unprecedented surge, analysts argue that Micron’s valuation remains compelling because earnings are rising even faster than the stock price.
Following a recent pullback from an all-time high of $455 a share, the surge in Micron’s stock looks poised to continue.
To that point, Micron is still seeing an eye-catching trend of positive EPS revisions, and has held a spot on the coveted Zacks Rank #1 (Strong Buy) list since this past August.
Micron’s Memory Products
Micron’s HBM (high-bandwidth memory), server-class DRAM (dynamic random-access memory), DDR5 (double data rate), and broader DRAM portfolio are seeing explosive demand.
Notably, AI chips from Nvidia, AMD AMD, and Alphabet GOOGL require enormous amounts of HBM, making it the single most supply-constrained memory type in the world right now.
DDR5 is the fifth generation of advanced synchronous DRAM and has been in short supply as well, making this category a major growth driver for Micron as the latest, fastest, and most efficient memory standard powering modern servers, PCs, and AI systems.
Reflecting the exceptionally favorable supply and demand dynamic, Micron’s FY25 sales hit a record $37.38 billion, with annual earnings near multi-year highs at $8.29 per share. And of course, top and bottom line peaks are projected this year.
Micron’s Blazing EPS Revisions
Wall Street expects Micron’s EPS to spike 300% in FY26 to a record $33.22, a staggering acceleration that reflects both pricing power and volume growth. Better still, FY27 EPS is projected to climb another 35% to a whopping $44.95.
Since most recently crushing earnings expectations for its fiscal first quarter in December, Micron’s FY26 and FY27 EPS estimates have continued to trend higher and are now up 78% and 91% in the last 60 days, respectively.
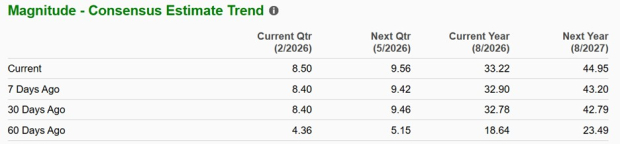
Image Source: Zacks Investment Research
Astonishingly, the year-ago earnings estimates picture shows that FY26 and FY27 EPS revisions have now skyrocketed 207% and 490%, respectively.
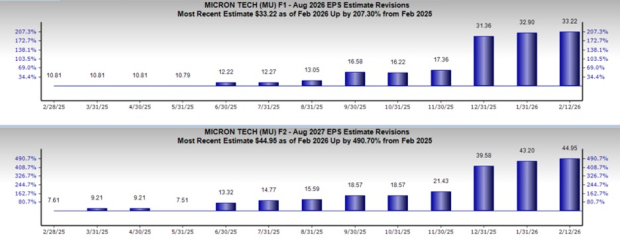
Image Source: Zacks Investment Research
Micron’s “Cheap” P/E Valuation
Just as captivating is that despite such an exhilarating rally, Micron stock still trades at 12X forward earnings. This is well below the rather stretched P/E premiums other high-growth tech stocks can command and offers a distinct discount to the benchmark S&P 500.
More intriguing, MU trades nicely beneath Sandisk Corporation SNDK and Western Digital’s WDC forward earnings multiples of 23X and 31X, as two of the other prime beneficiaries of the global memory chip shortage.
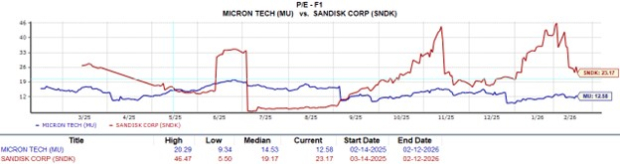
Image Source: Zacks Investment Research
Bottom Line
Micron has enjoyed exceptional pricing power, an advantage that strongly supports the continued momentum in its stock. Since being added to the Zacks Rank #1 (Strong Buy) list on August 20, 2025, Micron stock has soared a staggering 865%.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Aave Expands Stock-Backed USDC Loans on Base for Eligible Investors
Deciding Next Week’s Market Trend! The Biggest Uncertainty in the US Midterms: Republicans Unexpectedly Hold the Senate vs. Democrats Win Over 53 Seats
Citigroup believes that the expectation of a Democratic sweep of both chambers is largely priced into U.S. stock valuations, with control of the Senate being the key variable. If the Republicans unexpectedly retain the Senate, U.S. stocks may be boosted by year-end; if the Democrats win more than 53 seats, expectations of corporate tax hikes, fiscal negotiations, and regulatory risks for AI data centers will put pressure on the market.
The "Perfect Storm" Script for AI: Bond Market "Sounds the Horn," Earnings Reports "Add Insult to Injury," Will the Election Deliver the "Final Blow"?
The AI boom faces triple threats from the bond market, earnings reports, and political risks: rising financing thresholds have nearly closed the bond market for AI cloud companies; tech giants are increasing capital expenditures and experiencing deteriorating free cash flow, putting pressure on stock prices; with midterm elections approaching, growing opposition to data centers may push for tighter regulations. The market is shifting from pursuing computing power to questioning investment returns.

Will Solana expansion fuel ONDO’s price hike back above $0.50?
Crypto prices
More


