
Fabrinet Eyes 800ZR and Co-Packaged Optics as Growth Catalysts

Fabrinet’s FN next-generation 800ZR is a clear upcoming trigger. These products have not yet ramped, making production timing an incremental catalyst as Datacenter Interconnect (DCI) demand is expected to accelerate sequentially in the third quarter of fiscal 2026. Beyond the near-term ramps, FN is engaged in co-packaged optics with three customers and is also involved in optical circuit switching, with timing tied to customer roadmaps.
Datacom transceiver builds for hyperscalers directly and for merchant vendors are positioned as “quarters away, not years” from meaningful revenue, with second-source approvals serving as a gating item. Building 10 and the Pinehurst conversion are intended to reduce bottleneck risk as demand builds, and both are being funded without debt. That capacity readiness also supports potential share gains tied to the company’s second-source position on the AWS-related High-Performance Computing program.
Fabrinet’s EMS Model Limits Downside
FN’s pure-play electronics manufacturing services (EMS) model avoids margin stacking and does not compete with customers’ products, a positioning that can support program wins and help limit downside when mix and utilization shift.
Investors should watch for milestones, including evidence of DCI acceleration, 800ZR entering production and datacom constraint easing that sustains sequential growth. Additional confirmation points include High-Performance Computing (HPC) automation qualification supporting scale and how forex-related volatility flows through quarterly results.
In the second quarter of fiscal 2026, HPC contributed $85.6 million, and management expects the current program to exceed $150 million per quarter within the next couple of quarters, with double-digit sequential growth guided for the third quarter of fiscal 2026.
Fabrinet Offers Positive Q3 Guidance
For fiscal third quarter, Fabrinet expects revenues in the $1.15-$1.20 billion range. Non-GAAP earnings are expected between $3.45 per share and $3.60 per share, with sequential growth expected in Telecom, Datacom and HPC.
Fabrinet Revenue (TTM)
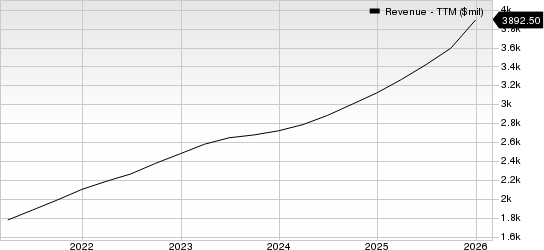
Fabrinet revenue-ttm | Fabrinet Quote
The Zacks Consensus Estimate for third-quarter fiscal 2026 revenues is currently pegged at $1.19 billion, indicating 36.2% growth from the figure reported in the year-ago quarter. The consensus estimate for the fiscal third quarter is pegged at $3.58 per share, up 3.5% over the past 30 days and indicating 42.1% growth from the figure reported in the year-ago quarter.
Consensus Estimate Trend
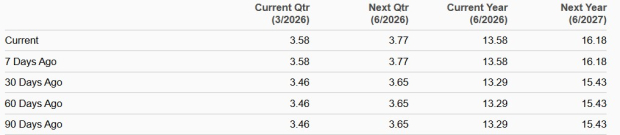
Image Source: Zacks Investment Research
Zacks Rank and Other Stocks to Consider
Fabrinet currently has a Zacks Rank #2 (Buy).
Advanced Energy Industries AEIS, Seagate STX and Western Digital WDC are some other top-ranked stocks in the broader Zacks Computer and Technology sector. All three stocks currently sport a Zacks Rank #1 (Strong Buy) each. Long-term earnings growth for Advanced Energy Industries, Seagate and Western Digital is pegged at 19.36%, 38.04% and 51.11%, respectively. In terms of share price movement, Advanced Energy Industries, Seagate and Western Digital have appreciated 215.1%, 292.7% and 486.7%, respectively, outperforming FN’s 192.1% return in a year.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Anthropic Adds 2 Sentences to Claude Code to Stop AI Video Game Clones
Ripple Partner Reaches One Million People With Safe Water
NASDAQ TRADE HALT CONTINUES <UCFIW.O> REASON NOT AVAILABLE AT 03:58 AM
 VIPCross-Asset Positioning Amid AI Earnings Scrutiny and the US Election
1. Markets diverged during the week. Between the October 23 and October 30 closes, BTC fell 4.78%, the Nasdaq 100 declined 1.98%, and gold and silver dropped 2.72% and 8.59%, respectively. The DAX, KOSPI, Nikkei 225 and Hang Seng advanced. We focus on differences in growth prospects, valuation sensitivity and risk exposures rather than applying a single directional view across assets. 2. Market reactions to Alphabet's and Intel's earnings brought returns on AI investment into focus. Attention is shifting from the scale of capital expenditure to revenue realization, margins and free cash flow. Lower interest rates can ease discount-rate pressure, but a sustained valuation recovery still requires support from both operating performance and financing conditions. 3. The November 3 US midterm elections and November 6 employment report are key events in the coming week. We monitor how post-election fiscal and legislative agendas may affect interest rates, the dollar and industry operating conditions. Our execution priorities are to manage leverage and concentration, retain margin and exit-liquidity buffers, and avoid treating a single political outcome as an automatic trading signal. 4. Following Binance's disclosure of a security incident, industry attention to endpoint protection, access segregation and coordinated incident response has increased. Key assets to monitor: BTC, the Nasdaq 100, crude oil and gold, alongside upcoming earnings from AAPL, AMD, PLTR, ARM, ANET and QCOM.

Crypto prices
More


