
Micron Technology (MU) Fiscal 2026 Q2 Earnings: Revenue Nearly Triples in Explosive Growth, EPS Significantly Beats Expectations, Q3 Guidance Midpoint Soars to Record-High $33.5 Billion!
 Bitget2026/03/19 02:45
Core Views
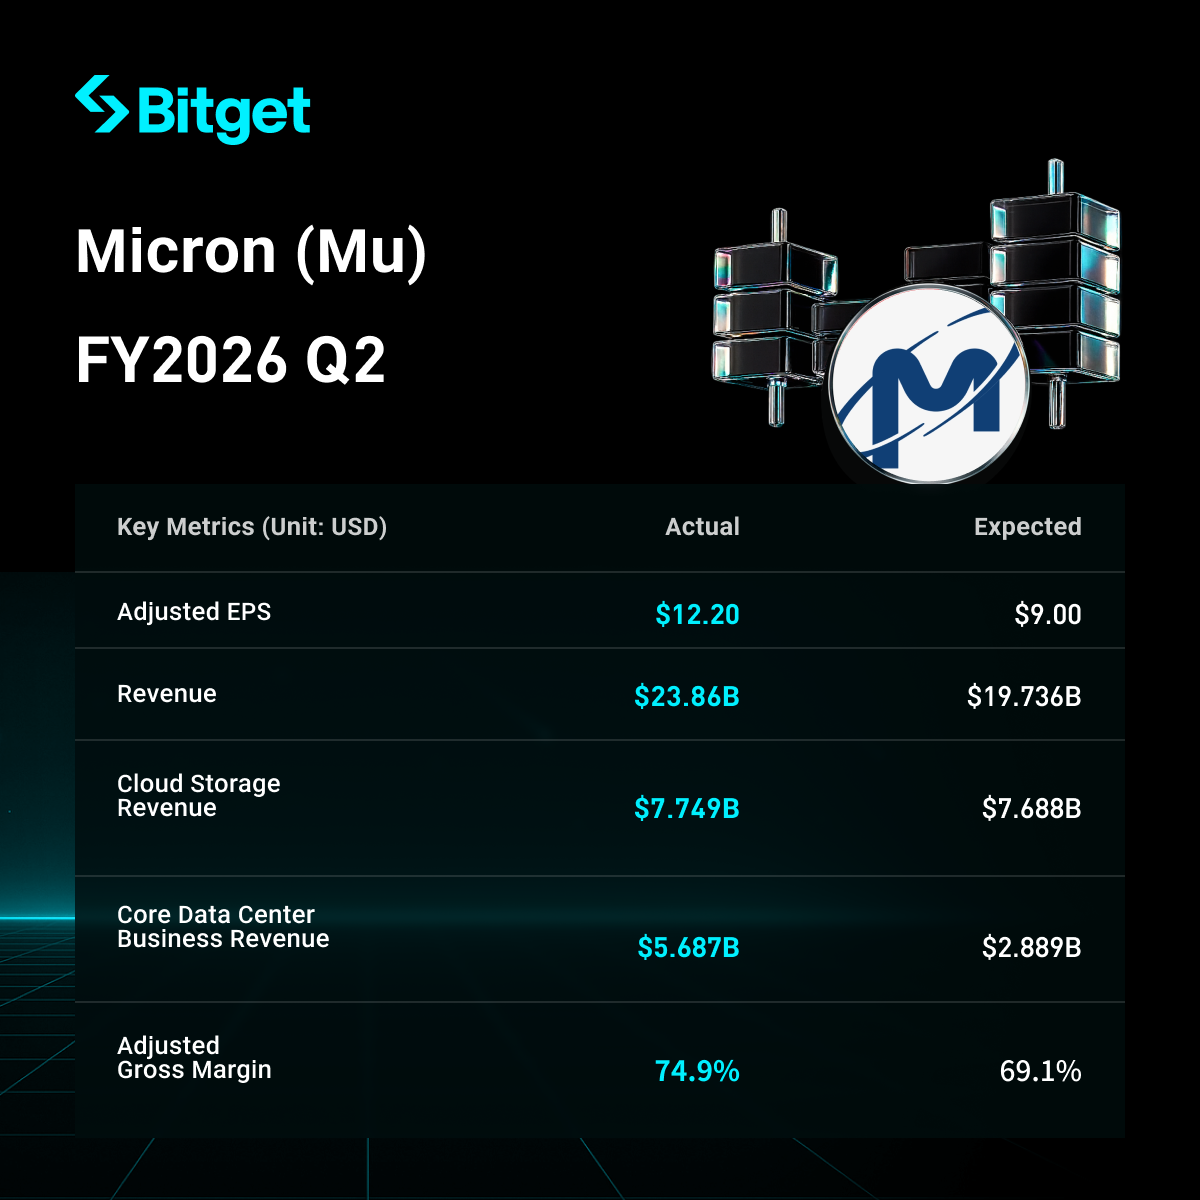
Micron Technology(MU) delivered a historic blowout in fiscal Q2 2026 (ended February 26, 2026), fueled by relentless AI-driven demand for HBM and data center memory. Revenue surged to a record $23.86 billion (+196% YoY, +75% QoQ), non-GAAP EPS reached $12.20 (far exceeding consensus ~$8.50–$9.00), and non-GAAP gross margin soared to a company-record 74.9%–75%. Free cash flow strengthened dramatically. Q3 guidance sets new highs with revenue midpoint $33.5 billion (±$0.75B) and non-GAAP EPS ~$19.15 (±$0.40), implying continued explosive growth. Despite the massive beat and raise, shares dipped in after-hours trading (down ~2-4% at points), reflecting concerns over the aggressive capex ramp-up and potential "sell the news" dynamics after a strong prior run-up.
Bitget now supports MUUSDT with 25x leverage contract trading—head over to seize volatility opportunities.
Current Bitget limited-time promotion: "Stock Newbie Gift, Zero-Fee Trading with 10 USDT"—trade more efficiently and cost-effectively!
Detailed Breakdown
- Overall Revenue and Profit Performance
- Quarterly revenue: $23.86 billion, +196% YoY (from $8.05 billion), +75% QoQ (from $13.64 billion) – fourth consecutive quarterly record, with the largest sequential dollar increase in company history ($10.2 billion).
- Non-GAAP diluted EPS: $12.20, significantly beating consensus (~$8.50–$9.21 range).
- GAAP net income: $13.79 billion, or $12.07 per diluted share.
- Non-GAAP net income: $14.02 billion.
- Non-GAAP gross margin: 74.9%–75% (company record), up sharply from prior quarter and YoY.
- Non-GAAP operating income: Strong expansion to record levels (operating margin ~69%).
- Adjusted free cash flow: Significant improvement, supporting robust liquidity.
- Operating cash flow: Strong sequential and YoY growth.
- Quarterly dividend: Increased (specific prior increase noted in context).
- Core Business Performance (Data Center & Cloud Memory – AI Driver) AI/HBM and data center demand remains supply-constrained, driving outsized growth and pricing power.
- DRAM revenue (core AI enabler): Record $18.8 billion, +207% YoY, 79% of total revenue; sequential bit shipments up mid-single digits.
- Cloud Memory and Core Data Center segments: Dominant contributors, with combined revenue exceeding 50% of total and high margins (gross ~74%, operating ~66-67%).
- HBM capacity for 2026 fully sold out, market share gains amid sustained multi-year tightness.
- Other Business Segments Performance
- NAND and other non-DRAM: Solid contributions (e.g., NAND ~$2.7B in recent context, +22% QoQ).
- Mobile, Client, Automotive & Embedded: Benefited from overall pricing tailwinds and mix shift toward higher-margin products. All segments showed margin expansion from improved industry dynamics.
- Future Plans (Capital Expenditure Guidance)
- Fiscal 2026 capex: Significantly elevated to support HBM/DRAM expansion for long-term AI demand.
- Heavy investment focused on capacity build-out to meet projected 4–5 year shortage in high-performance memory.
- Aims to capture market share and pricing upside, though scale of spending raises questions on near-term returns and cash flow allocation.
- Next Quarter Guidance (Fiscal 2026 Q3 Outlook)
- Revenue midpoint: $33.5 billion (±$0.75 billion), record high, massive YoY/QoQ growth far above prior expectations.
- Non-GAAP EPS midpoint: ~$19.15 (±$0.40), implying continued profitability surge.
- Non-GAAP gross margin: Expected ~81%.
- Management highlighted "substantial records" across revenue, margins, EPS, and free cash flow for Q3.
- Market Context & Investor Concerns AI data center boom continues to drive unprecedented memory demand, with HBM/pricing strength expected to persist for years. Micron positioned strongly with sold-out capacity and share gains. However, investor reaction mixed:
- Post-earnings volatility (initial gains then declines ~2-4% in extended trading) amid "sell the news" after prior rally.
- Concerns center on massive capex requirements potentially pressuring near-term margins/cash, cyclical memory risks, and high valuation already embedding much optimism.
- Core tension: Balancing explosive near-term growth/profitability with heavy long-term investment in a historically volatile sector.
Bitget now supports MUUSDT with 25x leverage contract trading—head over to seize volatility opportunities.
Current Bitget limited-time promotion: "Stock Newbie Gift, Zero-Fee Trading with 10 USDT"—trade more efficiently and cost-effectively!
Disclaimer: This content is for reference only and does not constitute any investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
US stock market AI goes down, Biden goes up! Berkshire hits another new high
BlackRock’s Ethereum ETF sees 580,145 ETH outflow, ETH holds above $2,209
Ethereum Is The ‘Toll Road To Tokenization’: Joseph Chalom’s Bull Case For ETH
Crypto prices
More


