
Even with a market capitalization of $5 trillion, Nvidia is still undervalued

Source: Global Market Report
Competition is intensifying, but the stock price of this AI chip giant remains weak, and the market has yet to fully recognize its industry-leading position.
The AI chip sector is no longer dominated solely by Nvidia, but it remains the undisputed leader and is likely to maintain this position for the foreseeable future—a competitive advantage that should be taken seriously by the market.
However, the market’s attitude has been quite the opposite recently. Even with impressive earnings reports and increasing capital expenditure expectations from major core clients, Nvidia’s performance within the chip sector has remained relatively weak this year.
Nvidia released its latest earnings report after market close on Wednesday, but even these strong results seem unable to reverse the current weak trend. According to FactSet, this marks the fourteenth consecutive quarter that Nvidia has exceeded Wall Street’s expectations for both revenue and operating profit, yet its after-hours stock price still fell by over 1% following the report.
UBS analyst Tim Arcuri believes that the market is now exhibiting clear indifference toward this AI giant, due to a complex mix of reasons.
Before the earnings release, Nvidia’s closing market cap had reached $5.4 trillion, firmly securing its position as the most valuable company in the world, far ahead of Alphabet, Google’s parent company, with a market cap lead of more than $700 billion. It’s worth noting that Alphabet boasts a massive and rapidly growing cloud computing business, strong in-house AI models, and a rapidly rising AI chip business as well.
This year, Intel’s stock price has surged over 200%, and memory chip manufacturer Micron Technology has gained over 150%, with its market value also approaching the trillion-dollar milestone.
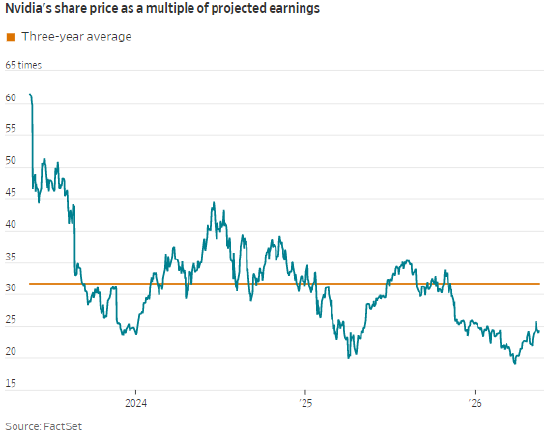
Even so, Nvidia’s unique robust growth outlook and currently reasonable valuation levels are still worth a fresh look from investors.
Among companies of similar scale, none can match Nvidia’s rapid growth—momentum that continues to accelerate. Nvidia expects revenue for the fiscal quarter ending in July to reach $91 billion, nearly double year-over-year. According to S&P Global Market Intelligence, among publicly traded companies with quarterly revenue exceeding $50 billion, the average year-over-year growth rate is just 14%.
Nvidia’s core business indeed faces increasingly fierce competition.
Demand for AI computing power is no longer exclusively reliant on Nvidia’s flagship GPU chips; companies like Intel, AMD, and Arm are finding opportunities for their CPU chips to enter the market.
In response, Nvidia has proactively adjusted its strategy, launching in-house developed CPU products that can be sold independently of GPU systems to meet varying customer needs. On Wednesday’s earnings call, the company revealed that revenue from its CPU business this fiscal year may approach $20 billion—a scale nearly matching Intel’s projected overall data center business revenue of $22 billion for the same period.
However, in the short term, GPUs will remain the main force in artificial intelligence computing power.
The IPO filing by Space Exploration Technologies Corp. on Wednesday serves as solid proof. SpaceX specifically highlighted that its massive data center is fully equipped with Nvidia’s top-tier Grace Blackwell computing systems—this GPU cluster is the core computing power for its xAI artificial intelligence business. Previously, xAI reached a partnership agreement with AI firm Anthropic, requiring the latter to pay over $1 billion per month in computing fees for the next three years.
There’s a major risk in the market: as SpaceX files for its IPO and OpenAI is about to launch its own IPO, capital will further chase these new AI-related stocks, potentially diverting attention from Nvidia.
But investors should pay closer attention to the true direction of capital flows. Last year, SpaceX’s capital expenditure on its xAI business alone reached $124 billion—three times its investment in the core aerospace business. Even though this segment is still operating with negative free cash flow, the company clearly stated that it will continue its high level of investment. This aerospace giant under Musk is just one of the many major clients driving Nvidia’s explosive revenue growth.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Gold price holds critical $4,100 support, but can it break $4,200 as inflation risks loom?
Hinkal joins Mastercard Crypto Partner Program for private stablecoin payments
Chipmaker earnings growth cools to 136% as AI boom lifts S&P 500
Updated: Delta Air Lines warns that as fuel prices hit profits, airline capacity will tighten further
Delta Airlines lowers its annual profit forecast due to an expected increase in fuel costs to $6 billion. The CEO stated that ticket prices have risen by about 20% this year, with limited passenger resistance. Analysts warn that maintaining high ticket prices in 2027 is critical for improving profitability. The article includes comments from the earnings call and analyst remarks. Rajesh Kumar Singh/Shivansh Tiwary, Reuters Chicago, October 9 - Delta Airlines (DAL.N) said on Friday that, despite strong travel demand and rising ticket prices, soaring fuel costs have forced it to cut its 2026 profit expectations by nearly a quarter. So, the airline industry may need to further limit flight growth next year to protect profitability. This warning highlights the increasingly tough challenges faced by U.S. airlines. While strong demand and restricted seat growth have allowed airlines to significantly raise ticket prices and offset higher fuel costs, aggressively increasing flights to capture more demand may intensify competition, making it harder to maintain high fares and protect profits. Based in Atlanta, Delta now expects its annual fuel expenditure to increase by about $6 billion compared to last year—about $2 billion higher than its July forecast—due to the Iran war (link) causing global jet fuel prices to spike. Airlines worldwide are preparing for a prolonged fuel shock. Michael O’Leary, CEO of Ryanair Group RYA.I, said Thursday that high jet fuel prices could persist for another 12-18 months (link), adding more pressure on airlines to raise fares and control costs. https://www.reuters.com/graphics/AUTOMATED-20261008/A4A-JET-FUEL-DAILY-1Y/xmpjwjnmbvr/chart.png “In a high-cost environment, you can’t simply grow your way out,” Delta CEO Ed Bastian said on the earnings call. He noted that the industry has already taken steps to restrict capacity, but more measures will be needed next year to improve profitability. Bastian said Delta raised ticket prices about 20% this year, and passenger resistance has been limited. He is confident that even if fuel costs eventually drop, the high fares can still be maintained. Delta lowered its adjusted annual earnings per share forecast from the July prediction of $6.50-$7.50 to $5.10-$5.60. According to LSEG data, the midpoint of the new range is below analysts’ average expectation of $5.46. Third-quarter adjusted earnings per share were $1.72, four cents below analysts’ average forecast. In midday trading, shares of Delta dropped 1.7%, United Airlines UAL.O fell 1.4%, and both American Airlines AAL.O and Southwest Airlines LUV.N were down about 1%. Delta partly shields itself from rising fuel costs by owning a refinery outside Philadelphia (link), which is expected to generate over $700 million in profits this year. Even with this buffer, the airline expects its fourth-quarter fuel price to rise from $3.61 per gallon in Q3 to $4.25 per gallon. Delta forecasts adjusted fourth-quarter earnings per share to be between $1.15-$1.65, with the $1.40 midpoint roughly matching analysts’ average expectation of $1.39. Fare increases Government data shows that in the first eight months of 2026, U.S. airlines spent $42.9 billion on fuel, an increase of $13.2 billion compared to the same period last year despite slightly reduced consumption. According to the U.S. Bureau of Labor Statistics, strong demand and limited seat growth pushed average U.S. airline ticket prices up by about 25% year-on-year between April and August. https://www.reuters.com/graphics/USA-AIRLINES/FUEL/lbpgdnbzwvq/chart.png Analysts at Melius Research said that despite surging fuel costs, Delta’s ability to raise fares helps keep second-half profits roughly stable. Still, they warn that the company’s profit margin has struggled to improve over the years. “It is critical for margin improvement to maintain or raise fares in 2027,” they wrote in their research report. With industry capacity growth expected to accelerate in Q4, this challenge will likely become even tougher. Deutsche Bank analysts expect the proportion of fuel costs recouped through revenue measures to fall in Q4 and predict full recovery won’t happen until early 2027. Bastian noted that low industry returns are another reason for limiting capacity growth. He said Delta will be cautious with its 2027 capacity plan until the fuel price outlook becomes clearer. He added that international routes may account for a larger share of Delta’s capacity expansion compared to domestic routes. Currently, Delta says its premium cabins and corporate travel business remain strong, and its economy cabin business is gradually improving. With Q4 ticket bookings already exceeding 60%, Delta expects revenue to increase about 20% year-on-year, despite limited capacity growth. Executives said early booking trends for Q1 2027 are also encouraging. (For the convenience of non-native English speakers, Reuters automatically translates its reports into several
Crypto prices
More


