
FET Exchange Supply Is Quietly Disappearing – Discover Why Traders Are Watching Closely

FET has been consolidating above $0.20 after weeks of sideways price action that has left the asset searching for a catalyst to force a directional decision. The price is holding but not advancing — and a CryptoOnchain analysis tracking Binance-specific flow metrics has identified a structural development in the exchange data that reframes what the current consolidation is actually building on.
Over the past week, the metrics governing FET’s exchange activity on Binance have contracted with a severity that goes well beyond routine fluctuation. The number of inflow addresses has plummeted by 92% — meaning the cohort of wallets sending FET to Binance has nearly vanished compared to the previous period. Total exchange inflows dropped by 71% over the same window. The combined effect pushed Binance netflow down by 557%, driving exchange flows deeply into negative territory.
Those numbers describe a specific and recognizable structural condition. The simultaneous collapse in both the volume of FET arriving on Binance and the number of participants doing the depositing is not ambiguous — it describes what CryptoOnchain identifies as an inflow drought. Fewer market participants are moving assets to the exchange, and the ones still active are moving considerably less than before.
In exchange flow analysis, that combination carries a direct supply implication — and it is the implication that changes how FET’s current consolidation above $0.20 should be read.
20% Reserve Depletion in 90 Days
The CryptoOnchain analysis extends the timeframe to reveal the pattern that gives the current inflow drought its full structural weight. The recent collapse in Binance deposits is not an isolated event occurring against a stable background. It is the latest development in a 90-day trend that has already depleted FET’s Binance reserve by 20% — a sustained, directional reduction in exchange supply that has been building quietly throughout the entire consolidation period.
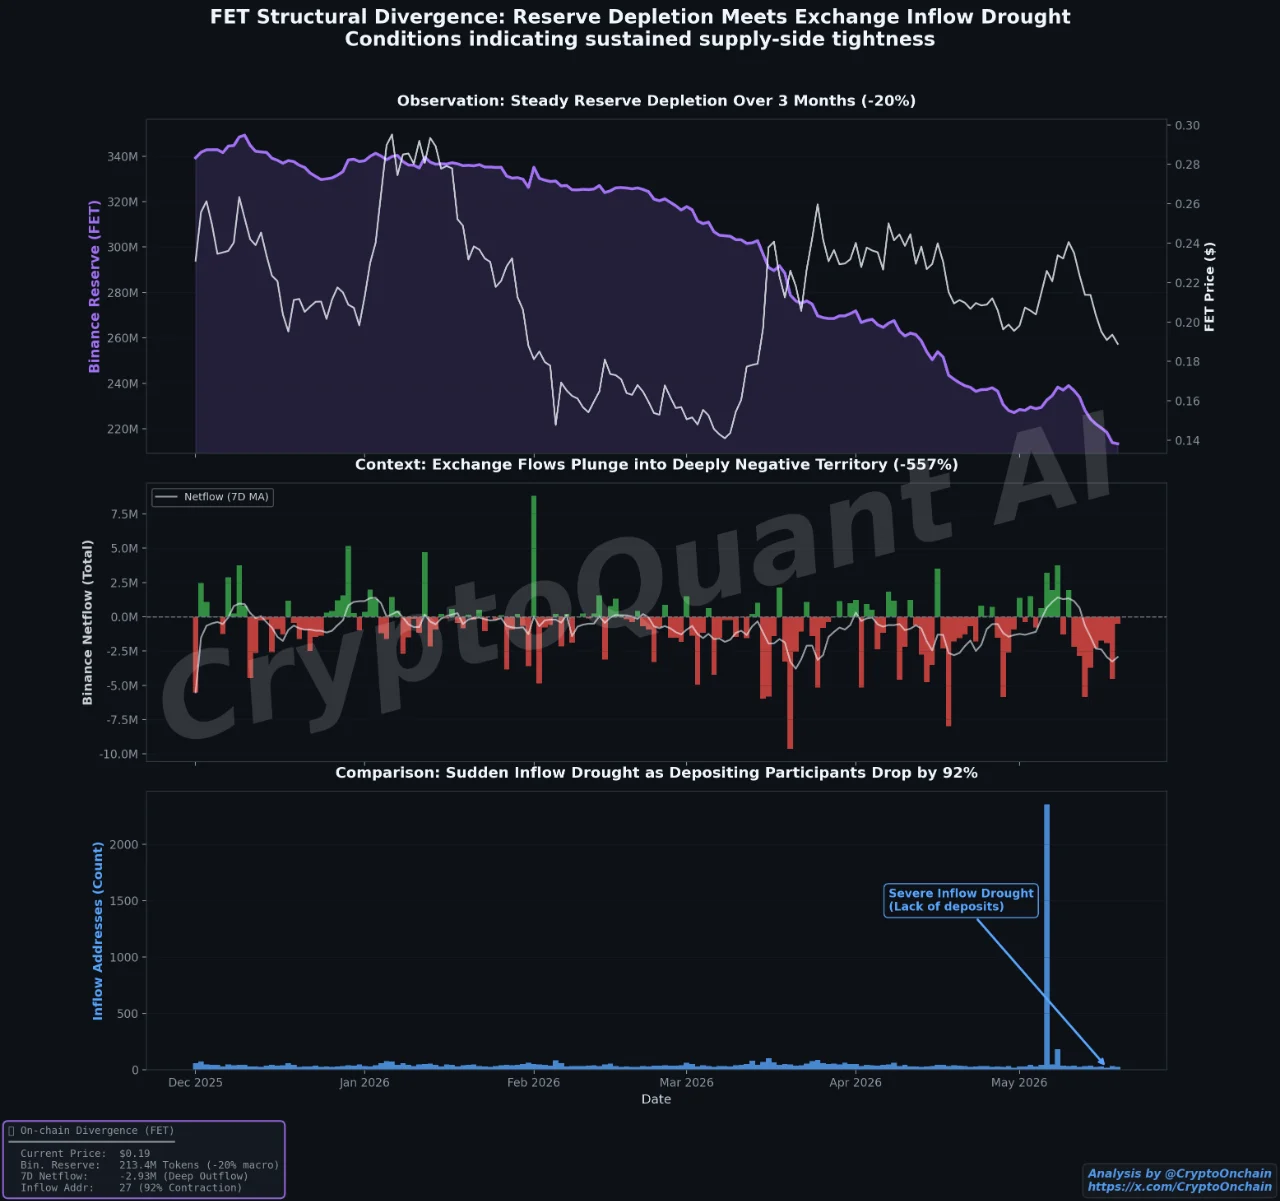
The combination of those two dynamics creates a supply imbalance that is more significant than either would produce independently. Exchange reserves declining over 90 days describes a market where more FET is leaving Binance than arriving on a sustained basis. The sudden halt in inflow deposits means the mechanism that would normally replenish that declining supply has effectively stopped functioning. The reserve was already shrinking. Now the pipeline feeding it has nearly closed.
Historically, the transition from stable exchange reserves to an inflow drought has created the conditions that preceded structural supply-side tightness — a regime where the available FET for immediate sale on the exchange continues declining without the fresh deposits that would restore the sell-side inventory. That tightness does not produce immediate price movements by itself. It creates the environment where demand, when it arrives, meets a thinner and thinner order book — and thinner order books amplify the price response to whatever buying pressure eventually emerges.
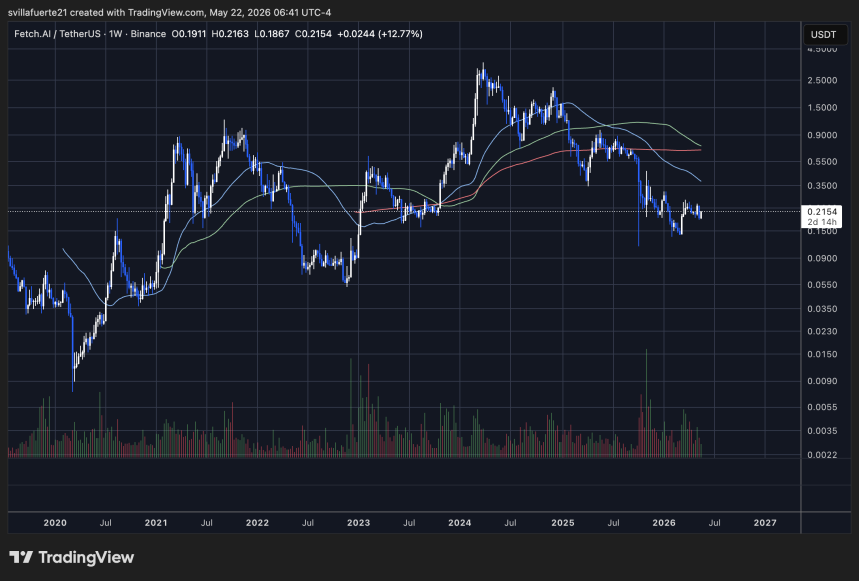
Technically, FET is still trading below the 50-week, 100-week, and 200-week moving averages, confirming that the broader macro structure remains bearish despite the recent rebound attempt. However, the intensity of the decline has clearly slowed. Recent candles show reduced volatility and lower selling momentum compared to the heavy distribution phases seen throughout late 2025.
The most important feature on the chart is the developing base structure around current levels. Buyers have repeatedly defended the $0.15–$0.18 region, while volume spikes during downside moves suggest periods of absorption rather than panic liquidation. This aligns with the Binance flow data showing severe inflow contraction and persistent reserve depletion.
For bulls, reclaiming the 50-week moving average near the $0.35 region would be the first major structural signal that accumulation is transitioning into trend recovery. Until then, FET remains in a prolonged rebuilding phase.
Featured image from ChatGPT, chart from TradingView.com
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Gold price holds critical $4,100 support, but can it break $4,200 as inflation risks loom?
Hinkal joins Mastercard Crypto Partner Program for private stablecoin payments
Chipmaker earnings growth cools to 136% as AI boom lifts S&P 500
Updated: Delta Air Lines warns that as fuel prices hit profits, airline capacity will tighten further
Delta Airlines lowers its annual profit forecast due to an expected increase in fuel costs to $6 billion. The CEO stated that ticket prices have risen by about 20% this year, with limited passenger resistance. Analysts warn that maintaining high ticket prices in 2027 is critical for improving profitability. The article includes comments from the earnings call and analyst remarks. Rajesh Kumar Singh/Shivansh Tiwary, Reuters Chicago, October 9 - Delta Airlines (DAL.N) said on Friday that, despite strong travel demand and rising ticket prices, soaring fuel costs have forced it to cut its 2026 profit expectations by nearly a quarter. So, the airline industry may need to further limit flight growth next year to protect profitability. This warning highlights the increasingly tough challenges faced by U.S. airlines. While strong demand and restricted seat growth have allowed airlines to significantly raise ticket prices and offset higher fuel costs, aggressively increasing flights to capture more demand may intensify competition, making it harder to maintain high fares and protect profits. Based in Atlanta, Delta now expects its annual fuel expenditure to increase by about $6 billion compared to last year—about $2 billion higher than its July forecast—due to the Iran war (link) causing global jet fuel prices to spike. Airlines worldwide are preparing for a prolonged fuel shock. Michael O’Leary, CEO of Ryanair Group RYA.I, said Thursday that high jet fuel prices could persist for another 12-18 months (link), adding more pressure on airlines to raise fares and control costs. https://www.reuters.com/graphics/AUTOMATED-20261008/A4A-JET-FUEL-DAILY-1Y/xmpjwjnmbvr/chart.png “In a high-cost environment, you can’t simply grow your way out,” Delta CEO Ed Bastian said on the earnings call. He noted that the industry has already taken steps to restrict capacity, but more measures will be needed next year to improve profitability. Bastian said Delta raised ticket prices about 20% this year, and passenger resistance has been limited. He is confident that even if fuel costs eventually drop, the high fares can still be maintained. Delta lowered its adjusted annual earnings per share forecast from the July prediction of $6.50-$7.50 to $5.10-$5.60. According to LSEG data, the midpoint of the new range is below analysts’ average expectation of $5.46. Third-quarter adjusted earnings per share were $1.72, four cents below analysts’ average forecast. In midday trading, shares of Delta dropped 1.7%, United Airlines UAL.O fell 1.4%, and both American Airlines AAL.O and Southwest Airlines LUV.N were down about 1%. Delta partly shields itself from rising fuel costs by owning a refinery outside Philadelphia (link), which is expected to generate over $700 million in profits this year. Even with this buffer, the airline expects its fourth-quarter fuel price to rise from $3.61 per gallon in Q3 to $4.25 per gallon. Delta forecasts adjusted fourth-quarter earnings per share to be between $1.15-$1.65, with the $1.40 midpoint roughly matching analysts’ average expectation of $1.39. Fare increases Government data shows that in the first eight months of 2026, U.S. airlines spent $42.9 billion on fuel, an increase of $13.2 billion compared to the same period last year despite slightly reduced consumption. According to the U.S. Bureau of Labor Statistics, strong demand and limited seat growth pushed average U.S. airline ticket prices up by about 25% year-on-year between April and August. https://www.reuters.com/graphics/USA-AIRLINES/FUEL/lbpgdnbzwvq/chart.png Analysts at Melius Research said that despite surging fuel costs, Delta’s ability to raise fares helps keep second-half profits roughly stable. Still, they warn that the company’s profit margin has struggled to improve over the years. “It is critical for margin improvement to maintain or raise fares in 2027,” they wrote in their research report. With industry capacity growth expected to accelerate in Q4, this challenge will likely become even tougher. Deutsche Bank analysts expect the proportion of fuel costs recouped through revenue measures to fall in Q4 and predict full recovery won’t happen until early 2027. Bastian noted that low industry returns are another reason for limiting capacity growth. He said Delta will be cautious with its 2027 capacity plan until the fuel price outlook becomes clearer. He added that international routes may account for a larger share of Delta’s capacity expansion compared to domestic routes. Currently, Delta says its premium cabins and corporate travel business remain strong, and its economy cabin business is gradually improving. With Q4 ticket bookings already exceeding 60%, Delta expects revenue to increase about 20% year-on-year, despite limited capacity growth. Executives said early booking trends for Q1 2027 are also encouraging. (For the convenience of non-native English speakers, Reuters automatically translates its reports into several
Crypto prices
More


