
21shares trims 2026 crypto forecasts despite institutional adoption gains

Asset manager 21shares has scaled back several of its bullish forecasts for the crypto industry this year, saying institutional adoption continues to strengthen even as weak market conditions and muted retail participation have slowed the pace of growth.
In its midyear outlook, the asset manager said the industry’s underlying infrastructure has advanced more quickly than prices. Areas such as exchange-traded funds (ETFs), stablecoin regulation, tokenization and prediction markets have continued to mature, but weaker crypto prices, major DeFi exploits and slower-than-expected enterprise adoption have pushed several of its 2026 targets out of reach.
One of the report’s clearest conclusions was that Bitcoin’s (BTC) four-year market cycle remains intact, despite signs the asset class is becoming more institutionally driven.
“After peaking at around $126,000 in October 2025, Bitcoin pulled back sharply and has continued to trade in line with prior post-halving patterns,” the analysts wrote, arguing that institutional ownership has softened market drawdowns but has not fundamentally altered Bitcoin’s cyclical behavior.
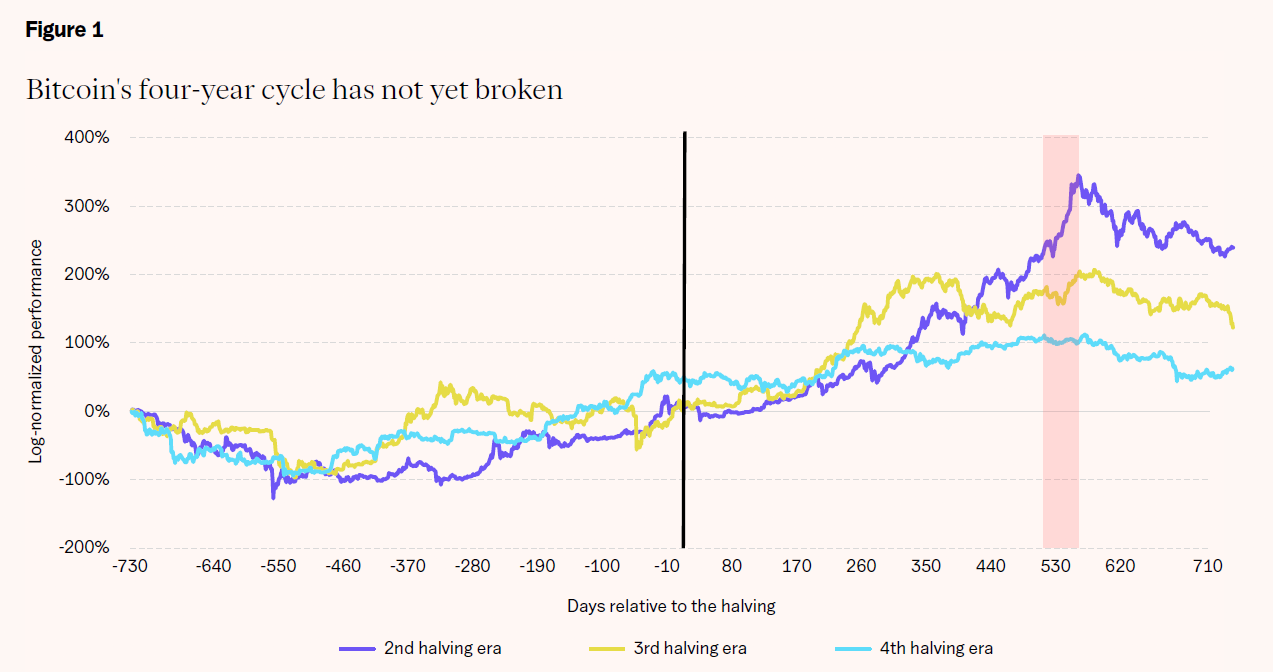
Bitcoin’s predictable four-year cycle continues to be a major driver of market conditions. Source: 21shares
Former 21shares co-founder Ophelia Snyder, who departed the company following its acquisition by FalconX in 2025, recently made a similar observation about how institutional investors have reshaped crypto markets.
“The investor base is larger, more institutional, and more connected to the broader financial system," Snyder wrote in a recent Substack post. “As a result, competing narratives, geopolitical developments, and macroeconomic shifts all have a much larger impact on crypto pricing than they once did.”
Prediction markets expected to outperform
Among the sectors outperforming expectations, 21shares singled out prediction markets as one of crypto’s strongest growth areas, projecting annual trading volume will surpass $100 billion this year.
The report also highlighted consolidation as a defining trend across the industry. Public companies holding crypto on their balance sheets are beginning to diverge, with many smaller treasury players trading below the value of their digital asset holdings, pointing to further consolidation in the sector.
A similar pattern is emerging across Ethereum’s layer-2 ecosystem, where a handful of dominant rollups continue to gain market share while dozens of smaller networks struggle to attract meaningful users and liquidity.
Related: Bitcoin miners need billions to fund AI ambitions, led by IREN’s $21B gap
Crypto ETFs show resilience despite outflows
That resilience is also evident in crypto exchange-traded products, which have continued attracting long-term institutional investors despite weaker market conditions.
While US spot Bitcoin ETFs have recorded roughly $3 billion in net outflows this year, 21shares said those figures don’t tell the full story. Holdings remain just above 1.25 million BTC, near an all-time high in for the token, suggesting many investors have held onto their positions through the downturn.
“Investors are holding through volatility or quietly building strategic positions, even with Bitcoin trading well below its highs,” the analysts wrote.
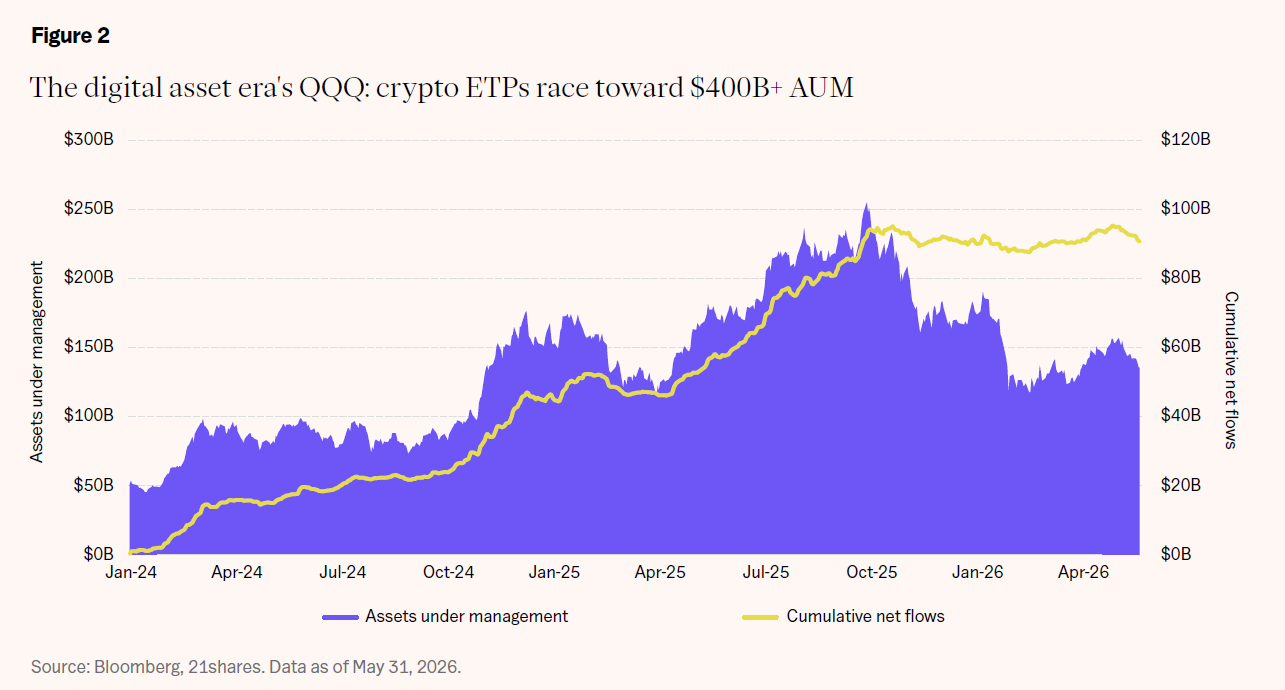
Crypto ETP assets have fallen from their peak, but cumulative investor inflows have remained resilient. Source: 21shares
The analysts also pointed to improving regulatory clarity in the United States, citing the Securities and Exchange Commission’s generic listing standards that have helped convert a backlog of crypto ETF applications into a steady stream of new product launches beyond Bitcoin and Ether.
“Hyperliquid stands out,” the analysts wrote. “US spot ETFs tracking the asset attracted over $150 million in net inflows in under a month, evidence that traditional capital continues to flow toward digital assets.”
Related: CBOE weighs converting BTC, ETH continuous futures into perpetual futures: Report
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Updated Version 4 - Mattel Investor Ariel Urges Sale Amid Stalled Turnaround
Ariel Investments holds a 5.4% stake in Mattel and believes the stock remains severely undervalued. Mattel stated it will take into account the opinions of Ariel and other shareholders. According to sources, Authentic Brands Group approached Mattel last week, with a potential valuation of around $6 billion. Analyst comments and a chart were added in paragraph 10. Juveria Tabassum/Angela Christy M Reuters, October 5 – A letter obtained by Reuters shows that a major shareholder of Mattel (MAT.O) on Monday urged the Barbie-maker to explore a sale, citing stagnant growth in performance and profitability. Ariel Investments, holding a 5.4% stake in Mattel, stated that the company’s stock is still severely undervalued. “We believe that strategic buyers would be willing to acquire your company at a price significantly above the current share price,” Ariel Co-CEO John Rogers wrote in a letter to Mattel’s board. The asset management firm suggested Mattel's options include “divesting significant assets, mergers, and/or an outright sale of the company.” Ariel believes other toy companies may be interested in Mattel’s asset portfolio, as well as entertainment firms and traditional private equity companies. In recent years, despite Mattel’s stabilizing business and the box-office success of the Barbie movie, the company has faced fluctuating sales and rising input costs. Operating profit has declined for six consecutive quarters. In after-hours trading, Mattel's shares rose 0.9% to $16.20. Ariel’s initiative comes as Mattel undergoes leadership changes (link). CEO Ynon Kreiz stepped down last month to become Co-CEO of Paramount Skydance (PSKY.O), while board member Roger Lynch—former editor-in-chief of Vogue and head of Condé Nast, parent company of The New Yorker—will assume the CEO role next month. Mattel replied to Reuters by email: “Our board and management team are committed to acting in the best interests of all shareholders, and will consider the views expressed in the letter from Ariel Investments, as well as those of other Mattel shareholders.” This is the second time this year investors have asked Mattel to consider strategic options. In May, Mattel investor Southeastern Asset Management called for the company to explore various options (link), including privatization, acquisition by competitor Hasbro (HAS.O), or by a major media company that could value Mattel’s assets more fairly than the public market. Last week, a person familiar with the matter told Reuters that Authentic Brands Group (AUTH.N) approached Mattel about a potential acquisition (link), which could value the toymaker at about $6 billion or higher. The source noted that there is no guarantee Mattel will accept Authentic Brands’ proposal, and the company is not conducting a formal sale process at this time. Following the news, Mattel’s share price soared. Despite the rebound, the stock remains down about 20% year-to-date. According to London Stock Exchange Group (LSEG) data, Mattel’s 12-month forward price-to-earnings ratio stands at 9.99, compared to an industry average of 14.03. “I think this just reflects the market’s frustration about the business possibly being a bit stagnant. Given the current level of valuation, now may be a good time to turn around the business away from the spotlight of investors,” said Morningstar analyst Jaime Katz. (For the convenience of non-English speakers, Reuters automatically translates its reports into several languages. As automated translations may contain errors or lack context, Reuters does not guarantee the accuracy of automated translation texts and provides them solely for readers’ convenience. Reuters assumes no liability for any loss or damage resulting from the use of the automated translation feature.)
42% premium, five years to break even with capital cost, Schneider Electric sets record with $23 billion acquisition of PTC, stock price plunges
Schneider Electric’s acquisition of industrial software company PTC marks the latest move by European industrial companies to accelerate their bets on AI. While the strategic rationale is acknowledged by analysts, the financial cost of the deal is heavy. PTC is expected to generate only about $1.5 billion in operating profit by 2031, and the anticipated cost savings to be realized three years from now will only contribute an additional $280 million.
Custodia Bank CEO Caitlin Long warns tokenized deposits could outpace stablecoins
Spacex closed up 7.6%, reaching a new high since June, helping Musk "regain" his trillionaire status
SpaceX's stock surged nearly 8% on Monday, with Elon Musk's net worth rebounding to approximately $1.03 trillion, reclaiming the top spot on the billionaire list. Morgan Stanley released a bullish report, setting a target price of $300 and stating that the company's value is underestimated. The rally was driven by multiple catalysts, including expectations for Starship recovery, expansion of AI business, and over $12.7 billion in defense contracts.
Crypto prices
More


