
Ringgit: Leading Currency in Southeast Asia

Since Q4 last year, the Malaysian Ringgit has performed exceptionally well among Southeast Asian currencies, leading most of the time against the US dollar. Malaysia's sustained current account surplus, dual export advantages in technology and energy, stable monetary policy, and continuous capital inflows form the underlying logic for the Ringgit's outperformance among Southeast Asian currencies.
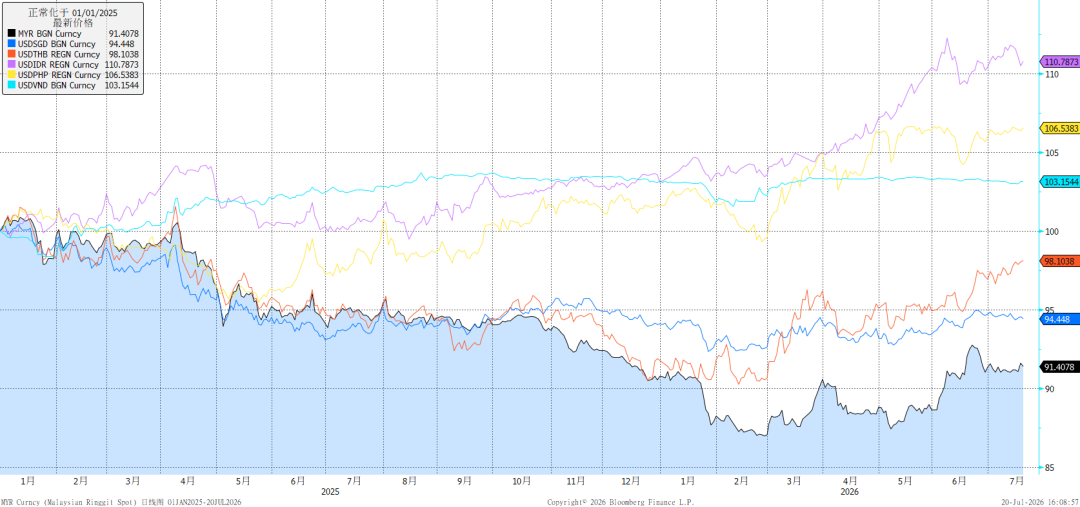
Performance of the Ringgit versus Other Southeast Asian Currencies Since 2025
First, from an interest rate perspective:
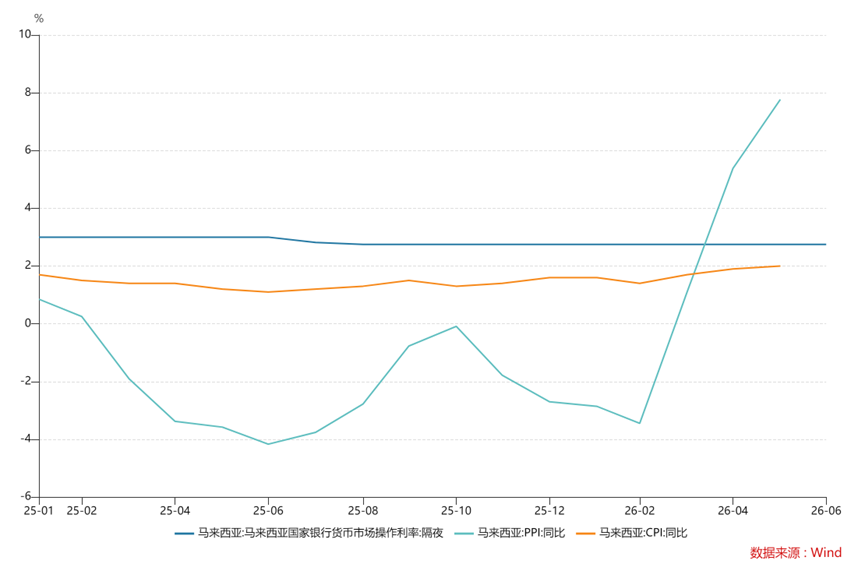
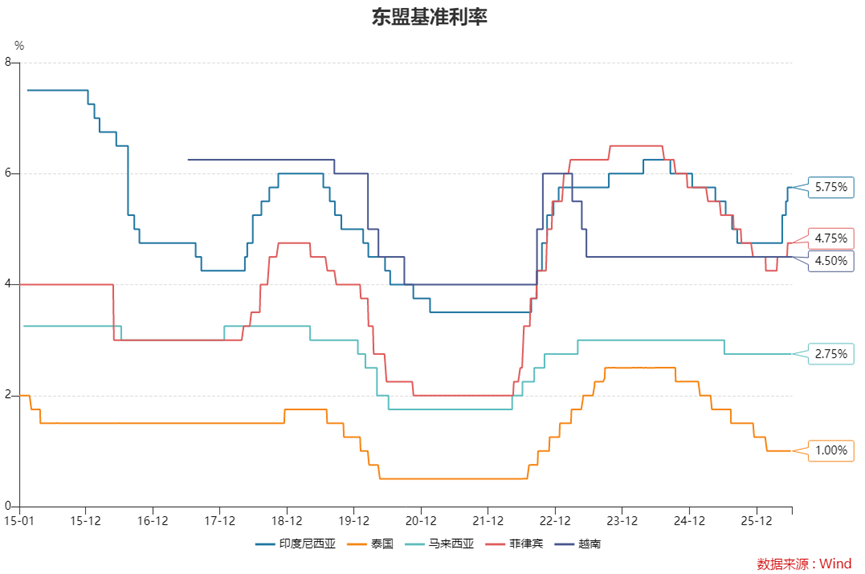
The Ringgit’s policy rate (2.75%) is not among the highest in Southeast Asia, but it stands out for its stability. At its latest policy meeting in July, the Central Bank of Malaysia kept the Overnight Policy Rate unchanged at 2.75% for the sixth consecutive time. Domestic fuel and food subsidies suppress imported inflation, and Malaysia’s CPI is expected to fluctuate between 1.4%–2.0% in 2026, much lower than the high inflation seen in countries like the Philippines and Indonesia, so Bank Negara Malaysia does not need to resort to aggressive rate hikes or cuts.
Malaysia’s CPI Remains Relatively Stable
Among regional currencies, Malaysia’s stability surpasses Indonesia and the Philippines, and can generate a positive interest differential over Thailand. Weak economic growth in Thailand, combined with ultra-low rates, has led to continued capital outflows and a much sharper depreciation compared to Singapore, Malaysia, and Vietnam. Indonesia (5.75%) and the Philippines (4.75%) have high rates to passively defend their exchange rates, but structural weaknesses in their fiscal and trade positions remain unaddressed, resulting in continued depreciation throughout the year. Singapore (tracking US Treasury yields) and Vietnam (4.5%) maintain neutral interest rates plus strong FX controls, resulting in very low volatility and only slight weakening.
From the balance of payments perspective:
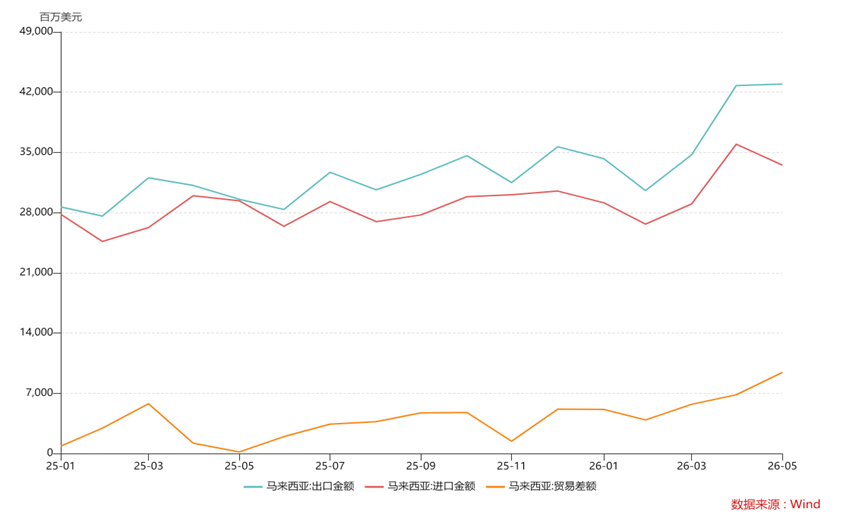
First, Malaysia’s imports, exports, and trade surplus have continued to expand. Malaysia is the only ASEAN country with both semiconductor and energy surpluses, which forms the fundamental support for the Ringgit exchange rate. In the first five months of 2026, the trade surplus reached MYR 132.8 billion, while Thailand and the Philippines have remained in deficit for years.
On a sub-sector basis, electronic and electrical exports (accounting for 44% of total exports) and increased AI chip/packaging and testing orders have boosted USD inflows; as a net exporter of crude oil and natural gas, the Ringgit is positively correlated with oil prices: when Brent > $85/barrel, energy export revenues rise significantly.
Malaysia’s Imports, Exports, and Trade Balance
Second, Malaysia’s capital account continues to see sustained foreign inflows: Q1 FDI net inflows amounted to MYR 22.8 billion, and continued foreign investment supports both sovereign debt and the stock market; the 10-year government bond yield at 3.12% offers a clear carry advantage in low-inflation Southeast Asia. As of end-June, FX reserves stood at $132.6 billion, amply covering short-term external debt, with no risk of sovereign downgrades.
From a policy perspective:
First, fiscal policy continues to consolidate, reducing sovereign risk: The fiscal deficit will shrink from 4.1% of GDP in 2024 to 3.5% in 2025, with a further narrowing targeted for 2026. The Fiscal Responsibility Act constrains the ceiling on government debt, the deficit continues to shrink, and debt is kept within 60%. The structure of fiscal expenditures is being optimized: inefficient subsidies are cut, targeted support is provided for sectors such as semiconductors, new energy, and data centers, and the long-term capacity for foreign currency generation through exports is being expanded.
Second, foreign exchange management: counter-cyclical adjustments to prevent large swings in the Ringgit’s exchange rate. Malaysia practices a managed floating exchange rate regime and has reintroduced mandatory repatriation of overseas income (resumed in 2026). Enterprises are forbidden from holding US dollars in overseas accounts for extended periods, increasing market supply of dollars and supporting the Ringgit from the supply side. When Fed rate hike expectations spike and USD/MYR rises sharply, Bank Negara Malaysia can directly intervene, selling dollar reserves and buying Ringgit to curb speculative large-scale forward shorting of the Ringgit, smoothing volatility; when the Ringgit appreciates sharply, active intervention is avoided to prevent impacting exports.
Overall, the Ringgit’s strong performance among Southeast Asian currencies is mainly due to its stable and attractive policy rate; consistent twin surpluses on current and capital accounts; and prudent fiscal and foreign exchange management policies.
Looking to the second half of the year, while the Fed will maintain high rates, putting some pressure on the Ringgit, Malaysia's sustained twin surpluses on both current and capital accounts, combined with strong oil and semiconductor exports, should provide effective offsets. With weak momentum for either appreciation or depreciation, the Ringgit is expected to continue a stable monetary policy, with the exchange rate remaining range-bound and fluctuating between 3.9 and 4.2 against the US dollar.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
AI boom reshapes the wafer foundry landscape! UBS: Explosive demand accelerates advanced process expansion, mature process enters upward cycle
UBS stated in a recent research report that within the foundry market, the Total Addressable Market (TAM) for the N2 (2nm) node far exceeds expectations, A14 (1.4nm) production expansion is accelerating, and the upcycle for mature process nodes has already begun.
$1,999 Foldable iPhone Is Ready, but Apple (AAPL.US) Faces Over $5.7 Billion Patent Penalty
As Apple intensifies its efforts in foldable displays and AI business, it faces a haptic technology patent compensation ruling exceeding $5.7 billion. On September 25, a federal jury in California found that Apple's Taptic Engine, used in certain iPhone and Apple Watch models, infringed on two patents held by Taction Technology.
Prospects for the opening of the Hormuz Strait are overshadowed, Asian bonds under pressure: 2Y Japanese bond yield approaches 2%, 3Y Korean bond yield rises to highest level since 2022
With high oil prices, short-term bond yields in South Korea and Japan have risen.
5% US Treasury pressure weighs on global assets, while Australian government bonds open up a window for allocation? Fixed income giant Pimco calls the rate hike expectations too aggressive
Pacific Investment Management Company (Pimco) holds a constructive view on Australian bonds, believing that market expectations for rate hikes are too high. Pimco stated that the rate hike cycle in Australia has been "fully priced in," and cracks are beginning to appear in the economy, making Australian bonds look attractive, especially in the 5- to 10-year segment of the yield curve.
Crypto prices
More


