
【US Meme Stock】rS: Doubled off the lows. AI security orders are accelerating — is the trade on?
 2026/09/22 07:26
1. Why look at rS now? What story is the market telling?
SentinelOne (NYSE: S, Bitget rS) is an AI-native cybersecurity platform. From the April 52-week low of $11.81, the stock is around $23.85 — roughly +100%. The last week was even sharper: close of $19.75 on Sep 11, a +14.5% volume spike on Sep 14, a 52-week high of $24.26 intraday on Sep 17, then another close at $23.80 on Sep 21 (+5.73%).
The tape is no longer “just another endpoint antivirus name.” Enterprises are trying to replace manual SOC work with AI agents, and S sits on both sides of that shift: AI for security and security for AI. Q2 already showed growth still intact, margins expanding, and AI Security ARR up 3x year over year. High beta plus an AI-security tape makes it an event-driven swing, not a core hold. One thing up front: this is not a GME-style short squeeze. Institutions own about 85%–90%; short interest is only about 5% with ~2 days to cover. Trade it as a breakout/momentum sleeve, not as a squeeze. The stock is already near highs.
2.Fundamentals snapshot
U.S. AI cybersecurity company, headquarters in Mountain View, California. The core product is the Singularity autonomous security platform — endpoint, identity, cloud, data, and AI apps — built to detect, investigate, and remediate in a closed loop. Customers run from mid-market and enterprise into government and MSSPs (FedRAMP High and GovRAMP High). International revenue is about 39%.
3.Products and business:
- Singularity platform: AI-EDR / XDR; one security OS from endpoint to cloud.
- Purple AI: agentic investigation and response, compressing hours of analyst work into minutes. An IDC study in 2025 (8 customer interviews) estimated ~338% three-year ROI.
- Prompt Security: shadow AI, prompt injection, Agent / MCP permissions — so enterprises can use AI without leaking the crown jewels.
- Wayfinder Frontier AI Services: human + frontier-model managed defense. On Sep 3 it added OpenAI GPT-5.6-Cyber.
- SentinelOne Flex: consumption-style licensing; already more than 10% of total ARR within a year of launch.
- Data and cloud security: non-endpoint solutions are already more than 50% of ARR.
4.Key financials and operating stats:
- Market cap about $7.8–8.3 billion; price about $23.80–$23.85; 52-week range $11.81–$24.26, ~2% off the high.
- Q2 FY2027 (quarter ended Jul 31, reported after close Aug 27): revenue $292 million, +21% YoY, above guidance.
- ARR $1.218 billion, +22% YoY; net-new ARR $56 million, a Q2 record.
- Non-GAAP operating margin about 10%, up ~820 bps YoY; non-GAAP EPS $0.08, doubled YoY.
- Remaining performance obligations (RPO) $1.7 billion, +45% YoY.
- Customers with $100k+ ARR: 1,715, +13% YoY; NRR in that cohort improved for three straight quarters.
- AI Security (Purple AI + Prompt) ARR up 3x YoY; management wants this to become the next $100 million+ ARR category.
- Cash and investments $813 million, no interest-bearing debt.
- FY2027 guidance raised: revenue $1.202–$1.207 billion (~+20%); non-GAAP operating income $124–$128 million (~10% margin).
- Q3 guide: revenue $309–$311 million; operating income $38–$40 million (~13% margin).
- Short interest about 18.23 million shares, ~5.4% of float, ~2 days to cover; institutions ~85%–90%. The bounce is narrative + fundamentals, not a squeeze.
5.Recent catalysts:
- Aug 27: Q2 beat and a raise to full-year revenue and operating-income guidance.
- Sep 3: Wayfinder added OpenAI Daybreak / GPT-5.6-Cyber, plus code-risk analysis and compromise assessment.
- Sep 10: Goldman Sachs Communacopia — management on agentic security.
- Sep 16–19: LABScon, the company’s threat-intel conference, just wrapped; AI offense/defense was the room.
- Sep 14: +14.5% on ~16.3 million shares, about 2x the 3-month average; Sep 21 closed green again, above every short- and intermediate-term moving average.
- Street still has Susquehanna at $28 and Wedbush at $25; consensus target about $24.4, high $28.
6.Expectation gap
What the tape already believes: the move is large, price is pinned to the 52-week high, and most 12-month targets sit near $24 — i.e., the beat and the guide raise are in the price. Still GAAP-unprofitable. ~7x sales is not cheap for ~20% growth. Versus CRWD and PANW it is smaller and less branded. After the Aug 27 print it ripped after hours, then closed Aug 28 down ~5% — the classic “revenue beat, EPS guide conservative” fade. Bernstein cut the rating to Market Perform from Outperform on Sep 17.
What may still be mispriced: the market still values it like a legacy endpoint vendor, but more than half of ARR already comes from data, cloud, and AI security, and AI Security is growing 3x. RPO +45% and more seven- and eight-figure deals mean visibility is better than the headline revenue rate. If Purple / Prompt is proven as a new nine-figure ARR line, the multiple can re-rate. That is a medium-term gap, not a short-squeeze gap.
Already happened: Q2 beat + full-year revenue/margin raise + AI Security 3x + OpenAI model hookup + Goldman + LABScon.
Watch next: AI Security ARR disclosure, large / 7–8 figure deals, Flex mix, cloud and data growth, cyber-sector tape.
Hard date: next print is Q3 FY2027, early December. Third-party calendars cluster around Dec 3–8 after the close; wait for the company IR notice. That is the window that decides whether “AI security” is still a story or already a bookings line — and whether this tape can re-rate another step.
7. Levels
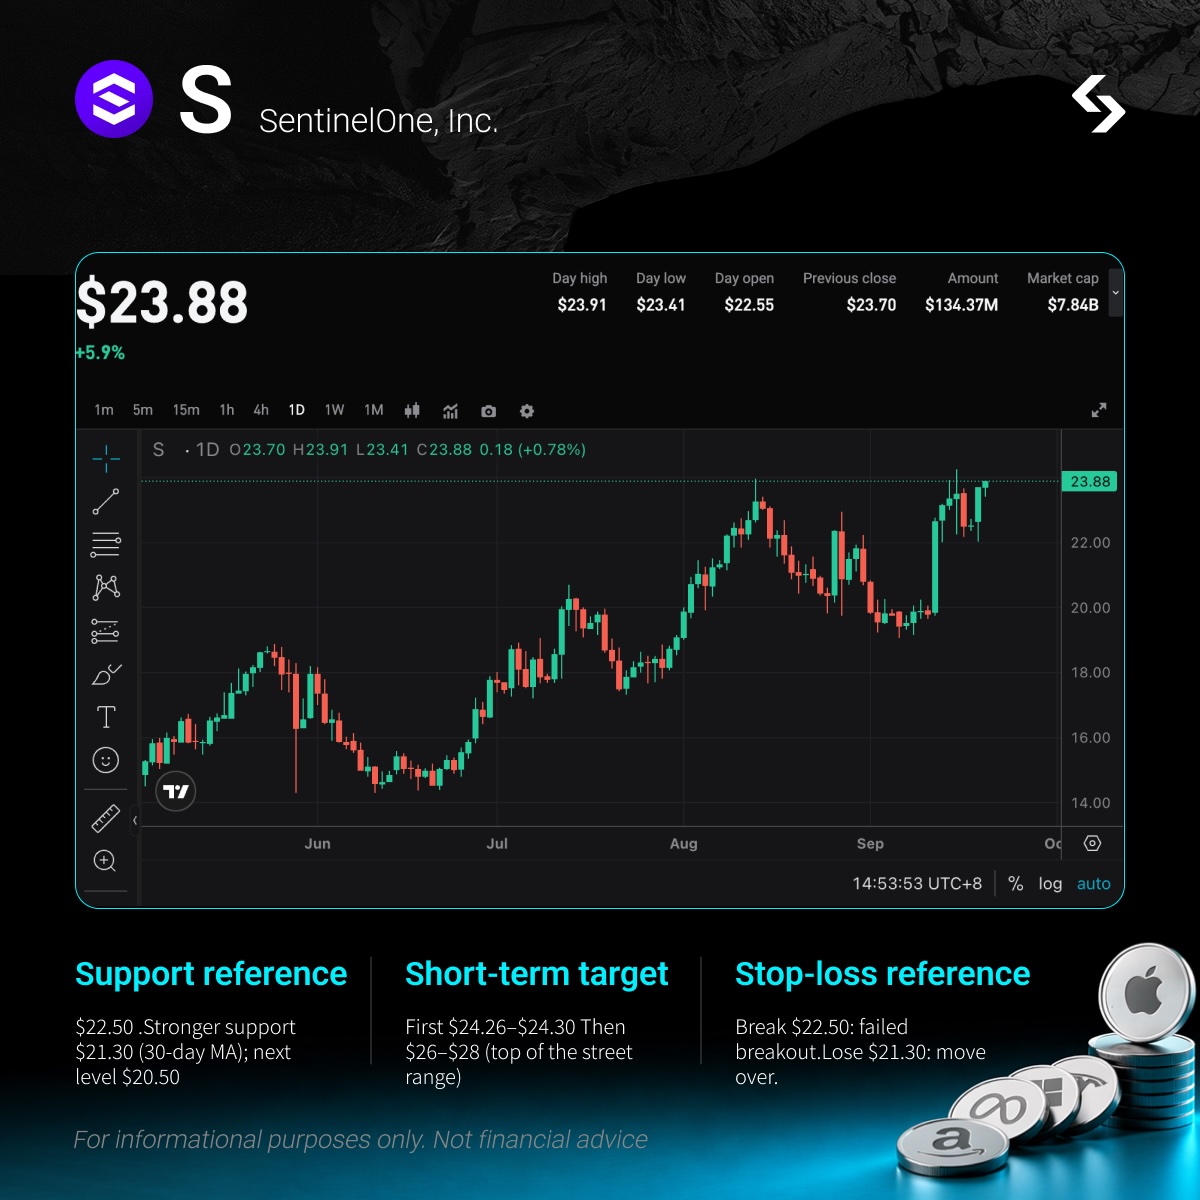
The setup is clean: AI-security adoption + platform mix lifting margins + the cyber complex running. Mid-cap, noisy tape — event-driven swing, not a chase through $24.
Support: ~$22.50 (Sep 18 low / 10-day area); stronger support ~$21.30 (30-day) and $20.50 (Sep 14 breakout).
Near-term targets: $24.30 first (clear the 52-week high), then $26–$28 (top of the street range).
Medium term: only discuss $30+ if AI Security stays triple-digit and the sector does not roll over. That is not a number to put in the trade card today.
Invalidation: a decisive break of $22.50 flags a failed breakout; lose $21.30 and the September impulse is done.
Note: already at highs. Size it as a satellite, not a core book, and do not stack it on top of rCRWD / rZS / rPANW.
8. Bitget-only convenience: rS trades 24/7
With Bitget rToken rS you can:
Get set without waiting for the U.S. cash open — catch after-hours and overnight moves
Follow the underlying with a transparent book and usable liquidity
Hold the tokenized line without babysitting a U.S. brokerage ticket
9. Risks
The main risk is a high-base fade and a stretched multiple. Price is less than 2% off the 52-week high; consensus targets offer almost no cushion. If the cyber complex cools, or December’s print shows AI Security decelerating, the giveback will be fast. Still GAAP-lossy. Competitive set is CRWD, PANW, and ZS; customer switching and price pressure can hit growth. Short interest is too thin to squeeze. This is an institutional name — after the headline impulse, volume can dry up and the stock can leak. High-beta name: size and stops matter.
The print and the AI tape have already lifted sentiment. Part of the growth story is in the price. The real argument is whether December delivery and follow-on orders keep up. Figures and levels are for reference only, not investment advice. Manage your own risk.
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
US Dollar Index pushes higher on the case for another Fed increase
SHIB Pay Expands Shibarium’s Payment Push
XRP rebounds 9% to $1.54, analysts eye resistance after “Uptober” narrative returns
Crypto prices
More


