
Sandisk (SNDK) Q1 Earnings Preview: Can AI Storage Growth and High Margins Deliver?
 2026/10/29 08:29
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
1. Investment Highlights Overview
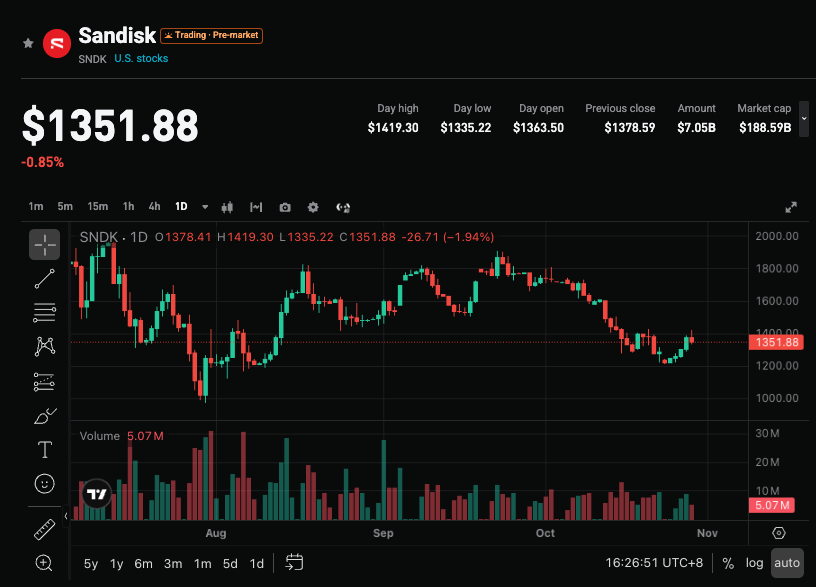
Sandisk (SNDK) will report its FY2027 first-quarter results after the U.S. market close on October 29, 2026, with the earnings call scheduled for approximately 4:30 p.m. ET. Company guidance calls for revenue of $10.3–$10.8 billion (midpoint ~$10.55 billion, ~+357% YoY), non-GAAP gross margin of 83%–85%, and non-GAAP EPS of $44–$46.
Wall Street consensus expects revenue of roughly $10.58–$10.72 billion (~+350% to +360% YoY) and EPS of about $46.2–$46.7. Against a backdrop of tight NAND supply and strong AI data center demand, the market is focused on whether revenue can reach or exceed the upper end of guidance, whether elevated gross margins can be sustained, and the contribution from the data center business and long-term contracts.
Focus 1: Extremely High Revenue Growth and Guidance Delivery
The midpoint of company guidance implies roughly +357% YoY growth, with consensus sitting slightly above the midpoint. In the prior quarter (FY2026 Q4), revenue reached $8.97 billion (+51% QoQ, +372% YoY). This quarter will test the company’s ability to sustain strong volume growth off a high base. Revenue approaching or exceeding $10.7 billion would reinforce the narrative of stronger-than-expected AI storage demand; results near the low end of guidance could raise concerns about the growth trajectory.
Focus 2: Gross Margin and ASP-Driven Profitability
The company guides for non-GAAP gross margin of 83%–85%, close to the prior quarter’s 84.6%. Sustained high NAND pricing, driven by AI data center demand, is the core driver; some analysts believe stronger-than-expected pricing could push results above consensus. Investors will watch the contribution split between pricing and volume, product mix (especially data center share), and the sustainability of elevated margins.
Focus 3: Data Center Business and Long-Term Contracts (NBM)
Data center has become a major growth pillar, with related revenue rising sharply in the prior fiscal year. The company has signed multi-year New Business Model (NBM) contracts with multiple customers, locking in substantial floor-priced revenue. The report will be watched for data center shipment and revenue mix trends, as well as the visibility provided by contract execution. Stronger-than-expected data center contribution would support higher valuation certainty.
Focus 4: Full-Year Outlook and Capital Return Signals
The market will focus on management’s commentary on subsequent quarters and full-year guidance, particularly NAND supply-demand dynamics, ASP trends, and capacity utilization. The company has previously strengthened its share repurchase program; capital return intensity amid high free cash flow is also a sentiment driver. An upward revision to the outlook or constructive comments on capacity and contracts could support the stock, while cautious guidance could pressure the elevated valuation.
3. Risks and Opportunities
Upside Catalysts:
- Revenue and EPS significantly exceed consensus (especially revenue near or above $10.8 billion and EPS above $47), accompanied by an upward revision to the outlook.
- Data center mix improves further, long-term contracts contribute more than expected, and gross margin holds at or above the high end of guidance.
- NAND pricing and demand signals remain robust, reinforcing expectations of a sustained AI storage upcycle.
Downside Risks:
- Revenue only meets the midpoint or low end of guidance and fails to beat consensus, raising concerns about slowing growth momentum.
- Gross margin declines sequentially or signs of ASP peaking emerge, compounded by profit-taking after the stock’s large prior run-up.
- Options-implied volatility is elevated (~10%–12%); muted results could amplify short-term downside.
4. Trading Strategy Suggestions
Bull Case: If revenue and earnings clearly beat consensus while management delivers positive commentary on data center demand, contract execution, and forward guidance, it could strengthen confidence in the NAND cycle and the company’s pricing power, supporting valuation recovery.
Bear Case: If key metrics merely meet or fall short of expectations, margins come under pressure, or guidance is cautious, the stock could face near-term pullbacks in a high-volatility environment.
Key Metrics to Watch:
- Total revenue and YoY/QoQ growth rates
- Non-GAAP gross margin and EPS
- Data center business performance and mix
- Whether subsequent-quarter or full-year guidance is raised
Operational Suggestion: Strong results with positive guidance may present pullback-entry opportunities; muted data or cautious guidance warrant caution on short-term volatility and chasing strength. Position sizing and stop-losses should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Crypto prices
More


