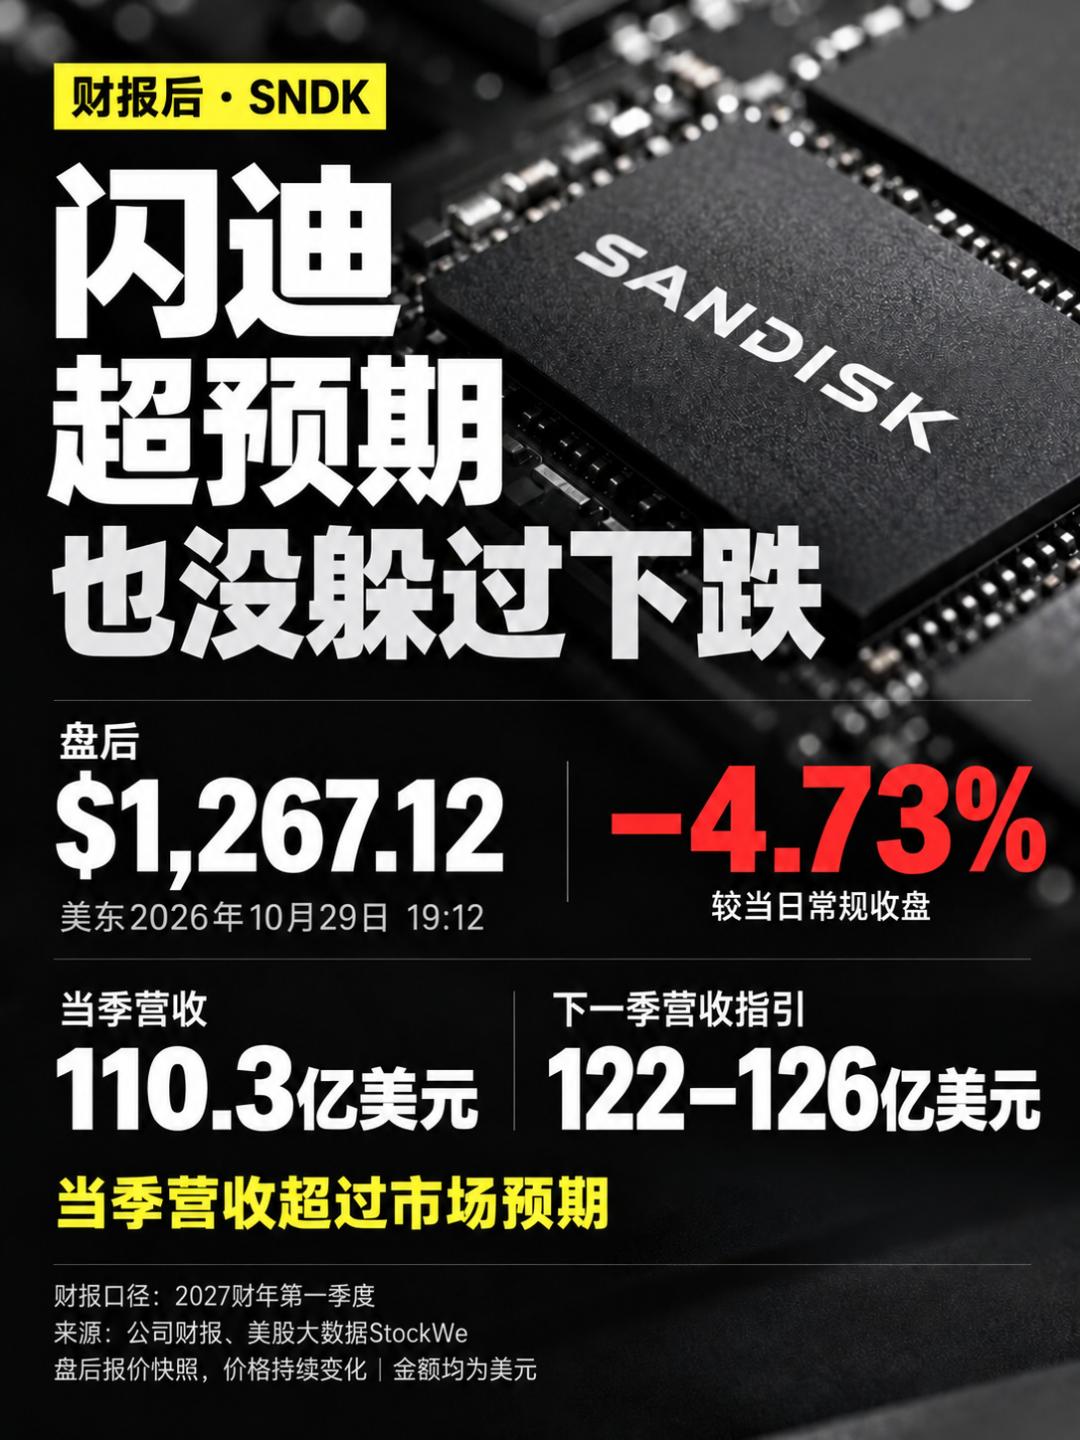
What makes this SanDisk financial report particularly frustrating for storage stockholders is: even with such impressive results, the stock still sold off after hours.
Quarterly revenue reached $11.03 billion, up 378% year-on-year; non-GAAP gross margin stood at 85.1%; data center revenue rose 61% sequentially. The company also announced a 1-for-8 stock split. Looking solely at these figures, it’s hard to conclude there is a lack of demand.
But the stock price always looks ahead to the next step.
According to US Stock Investing Network, storage stocks are transitioning from the stage of “shortages and rising prices driving continued earnings upgrades” into the stage of “how long can high profits last.” The business remains robust, but the market is starting to lose confidence in sustaining this profit level for the long term.
Two details clarify everything.
SanDisk’s revenue grew 23% sequentially this quarter, and next quarter guidance is at a midpoint of $12.4 billion, reflecting about 12% sequential growth. Gross margin this quarter is 85.1%, while next quarter guidance is 84.5% to 85.5%, with the midpoint essentially flat.
The company is still growing and expects high profits to continue. But what previously drove the stock price was that each quarter’s results were even more impressive than the last. Now, with revenue growth slowing and gross margins flattening, even if the absolute numbers are strong, the marginal surprises may be insufficient.
This does not mean the storage cycle is over, but rather that the market’s requirement for “outperforming expectations” has changed.
Here’s another crucial detail: management stated during the conference call that about 60% of this quarter’s sequential revenue growth came from volume, and 40% from price increases.
So, this financial report cannot be simply interpreted as “all driven by price hikes.” Actual shipments are still rising, which supports demand. But going forward, if the effect from price rises fades, the company will need to rely more on increased shipments, product upgrades, and lower costs to support profit growth.
For shareholders, this is more demanding than simply waiting for price increases as before.
This is also why, when storage stocks are delivering their prettiest results, investors may actually find them the most challenging. Once the market starts to fear a future profit decline, it will lower the valuation multiple it’s willing to pay, and the stock price can start weakening ahead of the earnings report itself.
Coming up, I’ll focus on three things:Whether NAND transaction prices can continue rising, whether client inventory is accumulating, and if, after new supply comes online, gross margin guidance starts getting revised down quarter after quarter.
The main risk is if shipments keep increasing, but both selling prices and profit margins weaken together. That’s when supply competition truly impacts the income statement.
As for the 1-for-8 stock split, it only lowers the per-share trading price—it doesn’t increase company value or change supply and demand.
I won’t conclude the cycle is over just because of one night’s drop, nor will I rush to buy the dip just because the stock is nearly cut in half now.
At this stage, I’m willing to wait for prices and profit expectations to gradually stabilize before considering adding positions. It is safer to miss a bit of the rebound than to treat peak-cycle profits as if they can be sustained long term.
If selling prices remain firm, clients keep purchasing, and profit margins remain solid—even if the stock is still pricing in a sharp earnings drop—then that’s when I would be more willing to act.
Conversely, if both selling price and profit margins are continuously guided lower, I’ll reduce positions and won’t use “AI is bullish long term” as an excuse for short-term profit deterioration.
My stance on storage stocks is now clear:I’ll keep interest in research and participation, but only increase my holdings if supported by operational data. The magnitude of the decline determines only whether I’ll open the financial report; how much I’m willing to buy depends on how much can be earned in the future.
Join US Stock Investing Network VIP
Get first-hand Wall Street news and exclusive quantitative research tools
US Stock Investing Network is a financial technology company specializing in US stock research, founded in Silicon Valley in 2008,by former NYSE analyst Ken, joined by several Morgan Stanley analysts and Google and Meta engineers leveraging AI and big data. Combining over a decade of US stock hands-on experience with industry quantitative models, they have built a stock market database that processes tens of millions of stock data points daily: tracking large options trades, real-time main capital flows, institutional holdings changes, and breaking Trump news.