
Buyers Disappear Amid AI Sell-off! Goldman Sachs Trading Desk Phones Flooded With Calls But No Takers, Hedge Funds and Retail Investors Withdraw Together

Goldman Sachs traders stated that Wednesday was one of the busiest trading days for their equities desk this year, while Thursday was the complete opposite. Investors were asking how much further the market could fall, but there was almost no buying activity; some hedge funds began selling stocks they had just bought on Wednesday. UBS data showed that Thursday's selling pressure mainly came from hedge funds. According to JPMorgan estimates, retail investors had a net sell-off of about $1.3 billion, marking the highest single-day volume in a year. The "fear index" VIX surged intraday to an eight-month high. Investors rushed to purchase protective options, and premiums for main equity index put options were twice the usual amount.
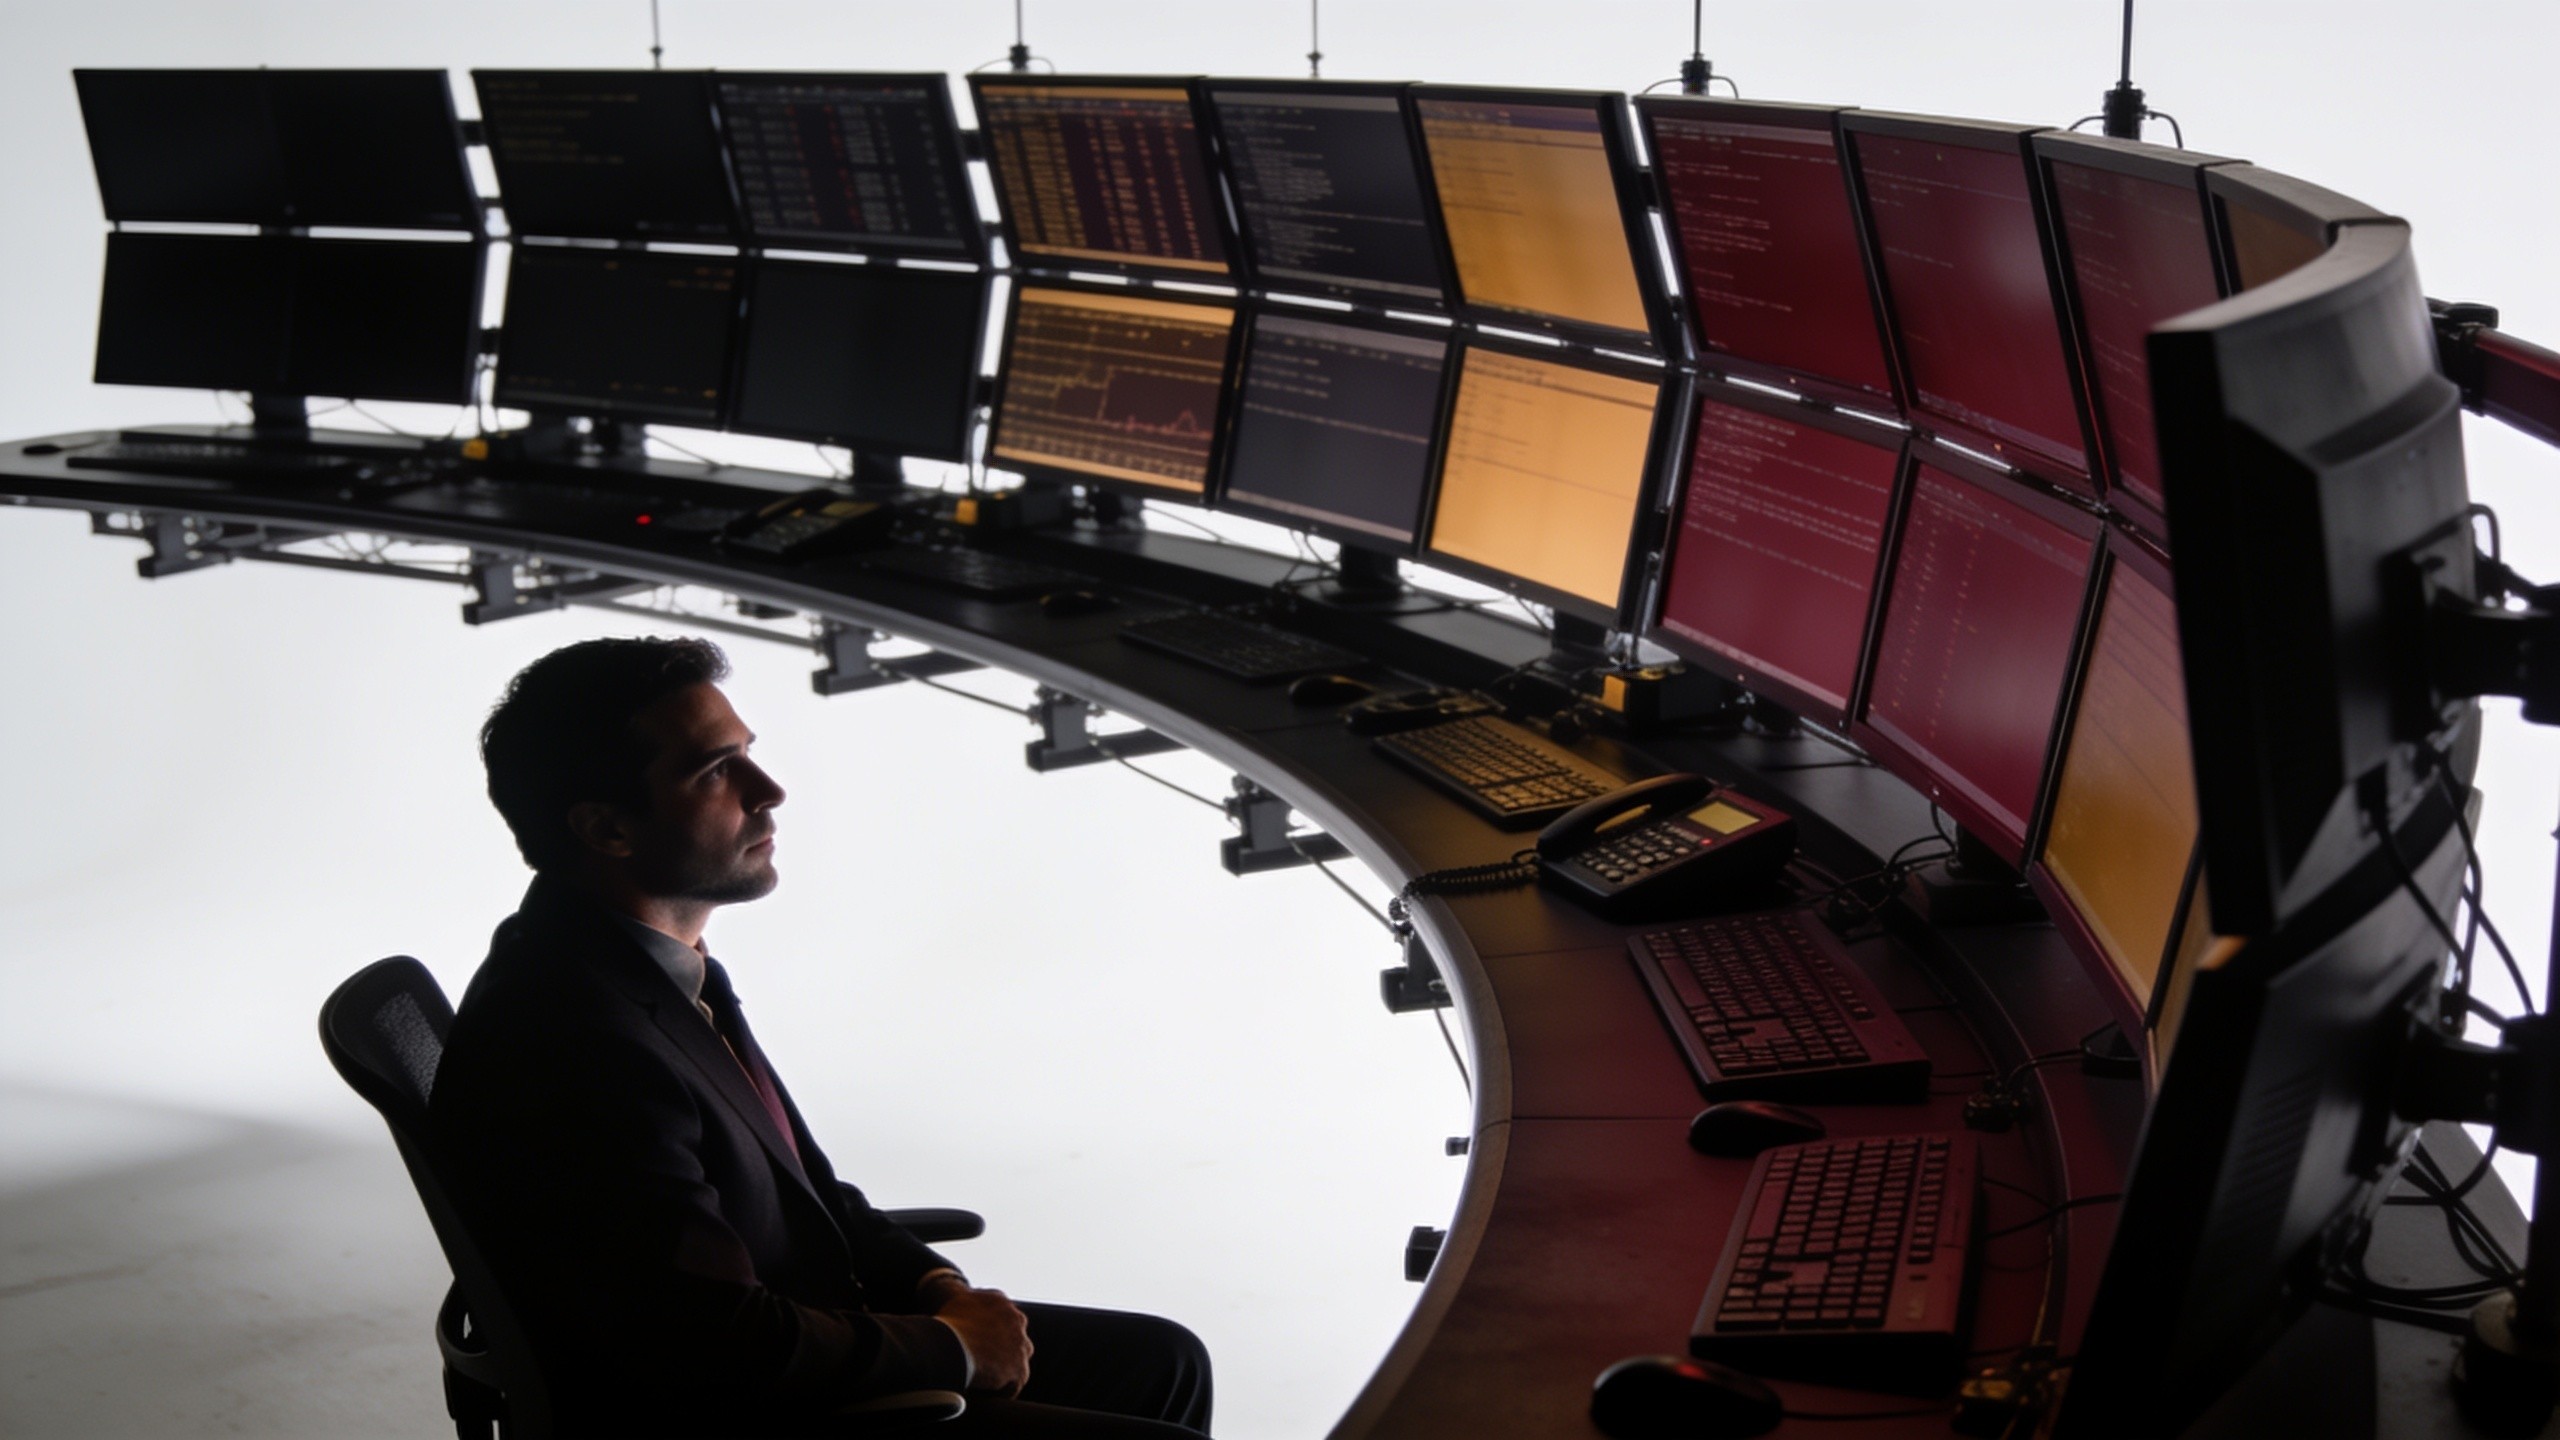
On Thursday, November 5th, Eastern Time, as U.S. tech stocks faced a sharp sell-off, the phone lines at Goldman Sachs' equity trading desk were almost overwhelmed, with investors calling in to ask how much deeper the market might fall. However, there were very few funds actually willing to buy the dip.
Goldman Sachs trader John Flood described in a market commentary to clients that Thursday’s trading environment was the exact opposite of the previous day: Wednesday was one of the busiest trading days of the year for the bank’s equity desk, while Thursday was "completely the opposite"—traders fielded a large volume of inquiries about the market, but saw almost no buy orders coming in.
This description reflects how, after the AI trading frenzy suddenly cooled, market sentiment shifted rapidly from chasing gains to risk aversion. The Nasdaq Composite Index closed down 5.52% on Thursday, the Philadelphia Semiconductor Index plunged more than 12%, and the overall market value of tech stocks evaporated by about $2.5 trillion. At the same time, volatility surged, retail investors concentrated on selling, and hedge funds cut their positions, further intensifying the market's decline.
Market Reversal Through Goldman Sachs Traders’ Eyes: Aggressive Buying on Wednesday, Rushed Retreat on Thursday
Flood noted that after Wednesday’s market rise, some investors who had significantly reduced their risk exposure ahead of the U.S. midterm elections re-entered the market and bought back some stocks. But on Thursday, as the market suddenly reversed, some hedge funds began selling off stocks just bought the previous day, particularly large-cap tech stocks and mega-cap tech companies.
He pointed out that long-term institutional investors once again adopted a wait-and-see approach, and the market had not yet seen buyers willing to step in and catch the falling knife. Meanwhile, brokers oriented towards retail clients also reported that for the second day in a row, sell orders noticeably outweighed buy orders.
Trading activity also turned unusual. Flood said that by mid-day Thursday, trading volume in the S&P 500 ETF SPY was about 160% higher than the average over the past 20 trading days; the volume for the Nasdaq 100-tracking QQQ was up about 100%; the semiconductor ETF SMH, up about 150%; and DRAM-related stocks, up about 75%.
The surge in volumes reflects that investors are intensively adjusting their positions, but does not mean all trades are net sales. Combined with the absence of strong buy-side activity described by traders, the clearer market signal is: When stock prices are falling rapidly, funds that might have otherwise stepped in chose to wait on the sidelines.
Institutional Selling Pressure Unleashed, Retail Investors’ Net Daily Sell Volume Hits Nearly a Year-High
The withdrawal of buyers observed by Goldman Sachs traders was also corroborated by other institutional trading data.
According to Reuters, data from UBS traders showed that on Thursday, the bank’s institutional clients were clearly net sellers, with selling pressure mainly from hedge funds, and tech stocks—especially in storage chips and semiconductors—facing heavy concentrated selling. UBS traders described the selloff in emerging cloud service companies and semiconductor stocks as an obvious "capitulation selloff."
Goldman Sachs traders also noted that on Thursday, hedge funds were selling off portions of large tech stocks they had just bought back the day before. The market not only saw sector rotation, but also investors directly reducing their overall risk exposure.
Retail investors also joined the exit. Data from Vanda Research indicated that on Thursday, the net sell volume in individual stocks by retail investors was likely to hit the largest single-day record since the pandemic. JPMorgan’s data as of 11:30 am ET showed that if ETFs are included, retail investors’ net sell volume reached about $1.3 billion, the highest level in the past year.
More notably, retail investors typically buy the dip during market declines, but this time, dip-buying in individual stocks clearly weakened. Vanda Research strategists pointed out that in traditional pullbacks, retail investors would usually buy the dip, but on Thursday, this buy-the-dip activity had actually vanished from individual stocks.
VIX Surges Intraday to Eight-Month High, Investors Rush to Buy Protective Options
In addition to equity selling, demand for hedging market risk also soared rapidly among investors.
The "fear index" — the Chicago Board Options Exchange Volatility Index (VIX) — surged by 11.75 points intraday on Thursday to 28.36, an eight-month high and the largest single-day intraday gain since the U.S. reciprocal tariff shock in April 2025; it closed at 28.18.
Changes in the options market also showed that investors were buying protection in case of further declines. According to data from options analytics firm Mercury Alerts, as cited by Reuters, on Thursday, the premiums paid for put options on major equity index products were about twice the normal level, reflecting a significant rise in demand for downside protection in the market.
Interactive Brokers chief strategist Steve Sosnick stated that market sentiment changed dramatically in just a day: on Wednesday, investors felt no need to buy protection, but on Thursday, they suddenly realized the need to hedge risks.
Additionally, leveraged and inverse ETFs and some quantitative strategies typically adjust their positions near the close based on market volatility, which could further amplify late-day market swings. According to intraday estimates from Nomura Securities, leveraged ETFs might need to sell about $47 billion in stocks before Thursday's close—this would be the second-largest sell-off of its kind since the bank began tracking the data in 2006, and the selling pressure is mainly concentrated in technology and AI-related funds.
This means that part of the selling was not entirely due to investors’ actively changing long-term views, but rather market declines triggering strategic position reductions, which in turn added further downward pressure.
Questions Raised About Data Center Construction and AI Investment Returns, Selloff Spreads From Chips to Supply Chain
The direct backdrop for this selloff was the substantial capital inflow and high market expectations previously accumulated by AI-related stocks, while the outcome of the U.S. midterm elections cast a policy shadow over the outlook for data center construction.
After the Democratic Party’s major victory in the midterms, the market began to worry that local governments and regulatory agencies might impose stricter approvals, energy, and environmental requirements on data center projects, thereby slowing down the construction of AI infrastructure in the U.S. Semiconductor, storage chip, emerging cloud service providers, and data center power suppliers all took hits as a result.
Goldman Sachs trader Flood also raised a more specific concern: by 2028, the market may face shortages of land, power, and construction capacity for data centers. If the construction of data center infrastructure cannot keep pace with chip deliveries, the market could shift from worrying about chip shortages to worrying about chip oversupply and a lack of enough data centers to absorb them.
This also explains why Thursday’s selloff extended beyond chip manufacturers: data center construction contractors, power suppliers, emerging cloud service providers, and other sectors also faced clear selling pressure. Investors are starting to reassess the growth pace throughout the AI supply chain and whether massive investments in computing power can actually be converted into revenue and profits as expected.
Meanwhile, the recent earnings outlooks from Qualcomm and Arm failed to meet market expectations, further undermining investor confidence in the semiconductor sector. The logic for long-term growth in AI demand has not disappeared, but the market's standards for the speed of growth materialization, capital expenditure returns, and the profitability of every link in the supply chain are rising.
For the market, the key issue has shifted from "How much more will AI investments grow?" to "Can these investments be completed on time, secure enough power, and generate returns sufficient to support current valuations?" When investors simultaneously choose to cut positions, hedge, and wait for buy opportunities, traders’ phones light up, but with no buyers stepping in—a vivid reflection of market sentiment during this round of AI selloff.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
The "Blue Wave" impact spreads to the mining sector, Trump administration-backed critical mineral deals face scrutiny
After the Democratic Party's sweeping victory, a key mineral deal supported by Trump is facing increasing pressure.
AUD/USD breaks 0.6950 as NASDAQ rout threatens key 0.6900 support
Dogecoin falls 7% to $0.071 as derivatives interest drops below $1 billion
Gold price rebound faces a test as US Treasury yields fall
Crypto prices
More


