
February CPI: Met Expectations, but Concerns Remain

Morning FX
The first CPI data after the US-Iran conflict has been released. Whether overall or core, year-on-year or month-on-month, all perfectly matched expectations, making it one of the most uneventful inflation figures in recent years.
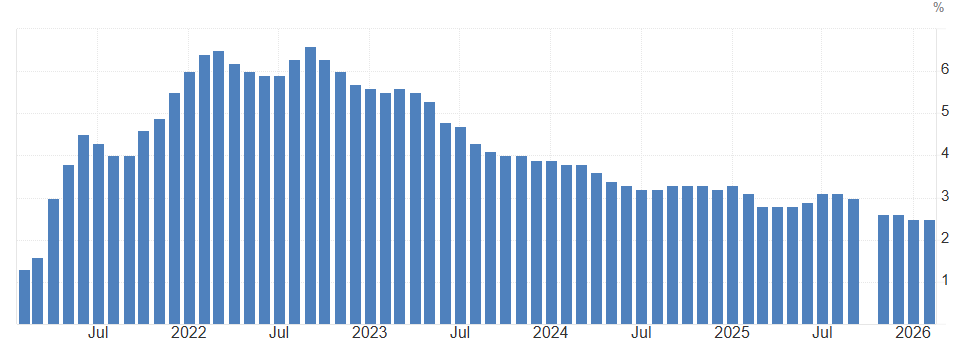
Chart: Core inflation hits a five-year low
At least before the war began, the disinflation trend has been continuing. February CPI grew by 2.4% year-on-year, while core CPI recorded the slowest year-on-year growth in five years at 2.5%. The core month-on-month figure dropped to 0.2%, indicating no sign of accelerating inflation.
I. Current Inflation Is Getting Closer to the Fed’s Target
Since the second quarter of 2024, the year-on-year CPI growth rate has officially entered the “2” era, with CPI growth at ≤3% for 20 consecutive months. Core CPI is cooling down simultaneously and is approaching the Fed's 2% target.
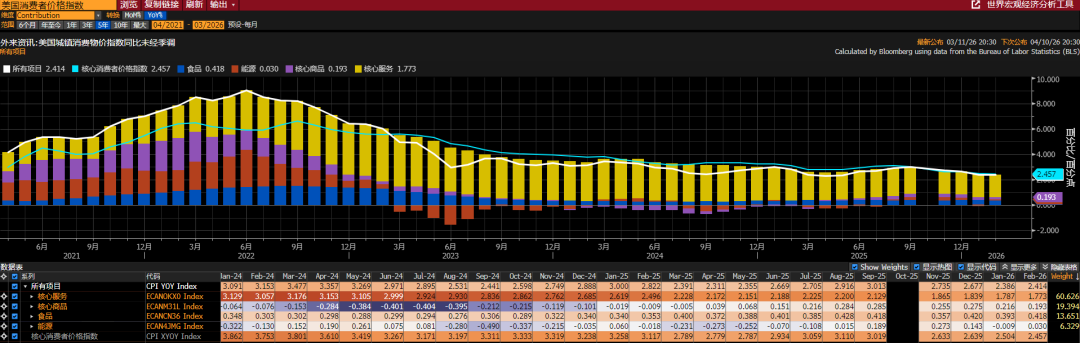
Chart: Inflation Subcategories
According to the latest data, the most stubborn core services contributed only 1.77% to CPI growth—a new low. Housing, which carries the highest weight among core services, as well as transportation and medical prices, have lost upward momentum, weakening inflation resilience.
Goods price increases have been mild as well, with core goods contributing just 0.19% to CPI growth. This means that as long as energy prices are under control, the potential for prices to rebound on their own is very weak.
II. Where Are Future Inflation Risks?
With employment visibly weakening, it should not hinder the Fed’s rate cuts. However, the market’s focus is clearly on soaring oil prices, and with fears of an inflation rebound, the room for rate cuts this year is very limited.
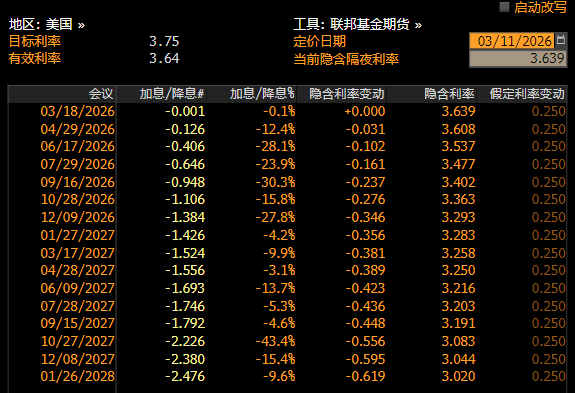
Chart: Rate Cut Room Remains Restrained
Trump launched a strike on Iran at the end of February so the oil price surge may only reflect in next month’s CPI. The Strait of Hormuz remains closed, and Saudi Arabia and the UAE are rerouting their crude oil exports.
Although the International Energy Agency (IEA) plans to release a massive amount of oil from strategic reserves, Brent crude has still climbed above $90. LNG shipments have plummeted to zero, which will undoubtedly continue to drive up overall energy prices.
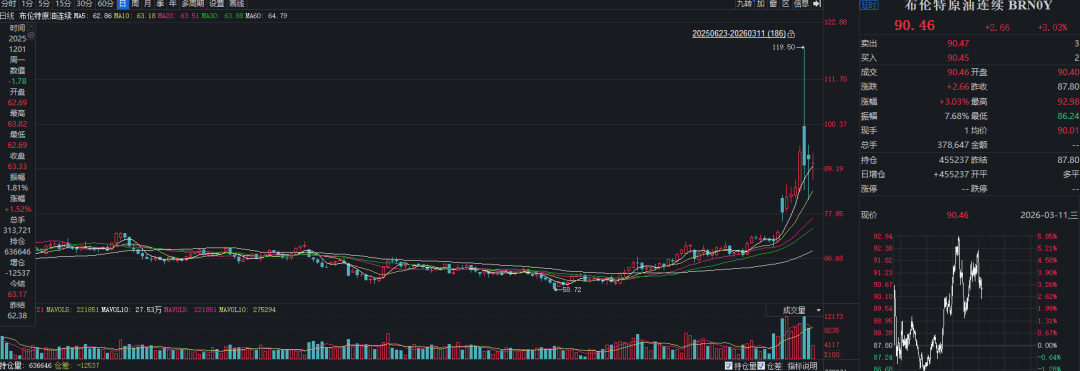
Chart: Oil Prices Remain High
According to Citi's observations, in the first two weeks of March, US gasoline prices rose by 17%, which may push the March energy sub-index’s month-on-month increase to 7%; producer prices and airfares are also expected to rise.
III. Summary
(1) February inflation continued its favorable trend, with core services price increases moderating and coming closer to the Fed’s target.
(2) However, the market has become numb to the data, focusing instead on skyrocketing oil prices. With the energy choke point at the Strait of Hormuz still blocked, the March CPI energy component is expected to be significantly affected, limiting the Fed’s ability to cut rates.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Q3 results exceed expectations + full-year guidance raised! Grab (GRAB.US) receives bullish rating from Citigroup after earnings: Stock price can still rise over 92%
Citi has given Grab a "Buy" rating with a target price of $5.50. This target represents a potential upside of over 92% compared to Monday's closing price of $2.86.
From "Powering AI" to "Powering Everything"! Morgan Stanley: The electricity "super cycle" is underestimated by the market
Morgan Stanley believes that the drivers of electricity demand have expanded from AI to three major forces: industrial migration and air conditioning refrigeration. Global electricity consumption is projected to reach 36 trillion kWh by 2030, with an annual growth rate of 4.2%. Asia will absorb 64% of the newly generated electricity demand. Fossil fuels have unexpectedly regained market share and are expected to still account for about 50% of the global power structure in 2030. Pricing power is shifting from equipment manufacturers to power generation operators, with wholesale electricity prices in major markets expected to rise by about 20% year-over-year in 2026. These trends will create $500 billion in wealth, driving related companies’ earnings per share forecasts up by 14% by 2028, while the market has yet to fully price in these changes.

Crypto prices
More


