
The worst quarter for gold in 13 years! The safe-haven myth is shaken as investors re-examine whether they should hold gold

Gold futures dropped more than 14% in the second quarter, marking their worst quarterly performance since 2013. According to a CNBC article, as an asset commonly used for portfolio diversification and risk hedging, gold’s recent performance has led some investors to question its effectiveness as a safe haven.
Since the outbreak of the Iran war, gold futures have declined by a cumulative 21%. Before this, gold prices had reached historical highs earlier this year. Charts show a contrast between the S&P 500 Index and gold futures over the past three months.
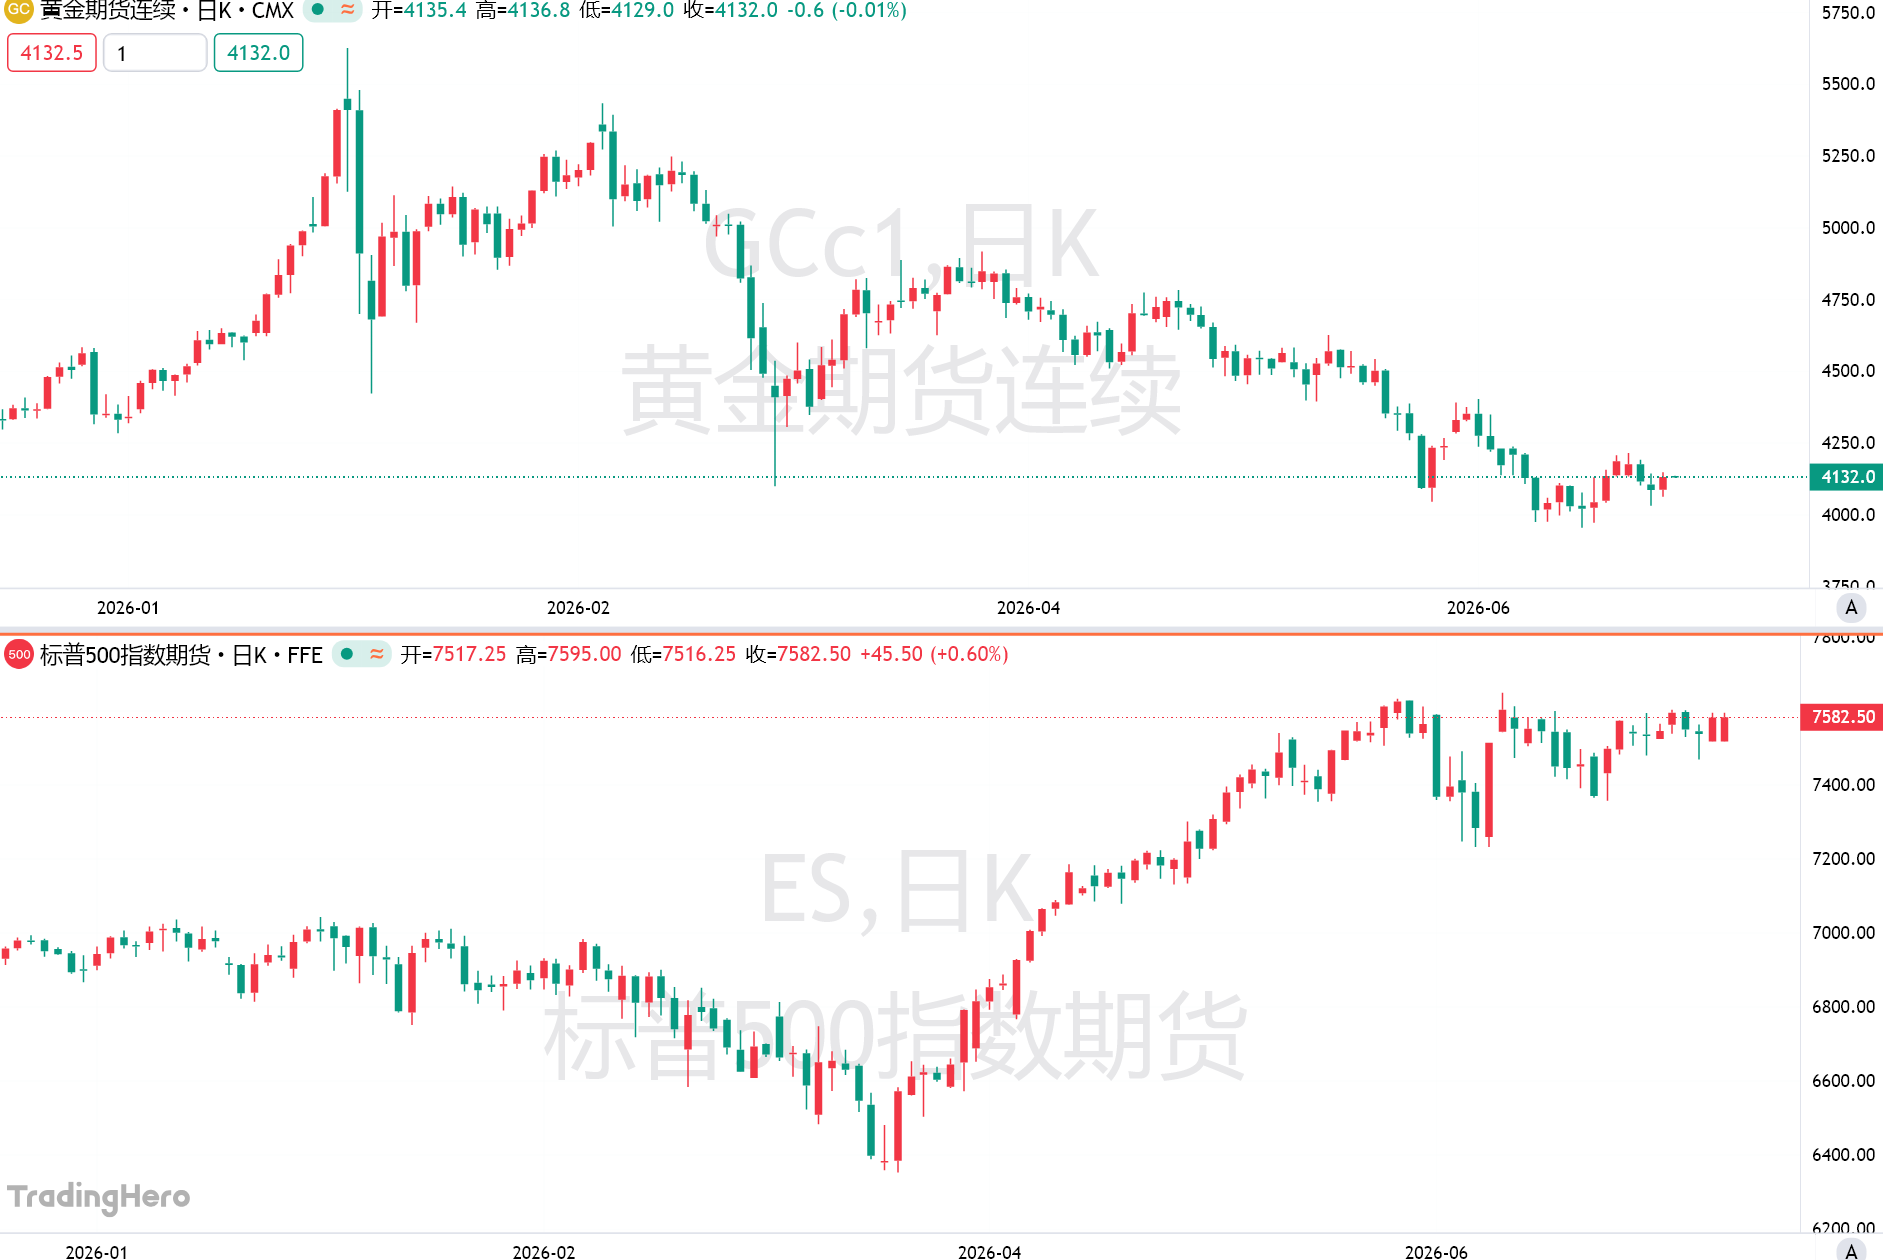
Gold’s recent performance is enough to raise concerns, but before investors remove it from their portfolios, it’s necessary to reassess their expectations for gold. The key issue is not merely a short-term drop in price, but rather the role gold is supposed to play in a portfolio.
Roger Aliaga-Diaz, Global Head of Portfolio Construction at Vanguard, said: “The hedging function does exist, but it may be less stable than people think. Not every time the stock market declines will gold conveniently rise and make up for the loss.”
Financial advisors point out that a common misconception among investors is to expect a persistent and direct inverse relationship between gold and stocks. In other words, when the stock market falls, it's not safe to assume that gold will definitely rise.
Sam Huszczo, founder of SGH Wealth Management in Lathrup Village, Michigan, Certified Financial Planner, said: “I don’t see gold as a direct hedge for the stock market, but it’s a great tool for hedging fear. With a small allocation, it serves as a decent diversification tool.”
Looking at long-term historical data, there are reasons to retain a certain proportion of gold in portfolios. An analysis by JPMorgan Private Bank shows that from 1985 to 2024, during and prior to major geopolitical shocks, the average four-week return for gold was 1.8%, with a median return of 3%. Over the same period, the average four-week returns of 10-year U.S. Treasuries and stocks both declined by 1.6%, with a median drop of 1.9% for both.
Aliaga-Diaz also noted that gold can serve as a tool for hedging U.S. dollar risk. He stated, “When the value or stability of the dollar, or the credibility of the Federal Reserve comes into question, you’ll most likely see money flow into gold.”
However, gold is not a low-volatility asset. Aliaga-Diaz stated that investors often overlook gold’s volatility, which in reality is quite similar to equities.
For this reason, gold exposures need to be kept within controllable limits. Most financial advisors recommend that gold allocations should not exceed 5%.
Losing money on gold in the second quarter doesn’t necessarily mean investors should sell off the asset class entirely. What matters more is assessing gold’s role in long-term plans, one’s personal tolerance for volatility, and whether its current allocation is too high.
Rafia Hasan, Chief Investment Officer of Perigon Wealth Management, said: “You should think about gold allocation over a longer time frame, not focus on just a quarter’s performance in isolation.”
Hasan recommends keeping gold allocations between 1% and 2%. She added: “I think commodities, as a broader diversification tool, indeed have their potential role. That said, commodity prices tend to be more volatile. I think last quarter just proved that point.”
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Silver price retreats as rising US yields, Hormuz tensions bolster US Dollar
U.S. August JOLTS job openings fall to a 5-month low, missing expectations for the third consecutive month
In August, job openings in the United States fell to 7.079 million, below economists' expectations of 7.228 million. Job vacancies in the real estate and rental sector were only 50,000, nearly halved from the previous month. The quit rate remained at 1.9%, matching the lowest level since 2020. The ratio of job vacancies to unemployed persons dropped to 1.0. Analysts have noted that net hires implied by the JOLTS report have been lower than the nonfarm payroll report for three consecutive months, indicating a significant downside risk for this Friday’s nonfarm payroll data.
CLARITY Vote Wasn’t the End: 5 Altcoins to Watch Before the Next Crypto Catalyst
AI Predicts Bitcoin Path as Strategy Moves 3,568 Coins
Crypto prices
More


